Geely Automobile Holdings - 1H26 results briefing takeaways

Related Stories

- 1H26 core net profit rose 46% y/y to RMB9.7bn, with gross margin expanding 1.5ppt to 17.9% on stronger Zeekr and export mix
- Management raised FY26 export guidance to 920k units, but we see upside to c.1.1mn given 7M26 exports have already reached c.580k
- Management reshuffle should have limited operational impact, with Li Shufu remaining Chairman of parent Geely Holding as the group further professionalises management structure
- Maintain BUY; raise TP to HKD29 (pegged to 11x rolling PE) on stronger export assumptions, current 8x rolling PE is attractive
Solid 1H26 results reinforce Geely’s strategic progress. Geely reported an in-line set of 1H26 results, with core net profit rising 46% y/y to RMB9.7bn. Revenue grew 15% y/y, while gross margin expanded a healthy 1.5ppt y/y to 17.9%, which we view positively given ongoing raw material cost inflation. We attribute the improvement largely to a more favourable sales mix, supported by strong growth in premium brand Zeekr (+97% y/y in 1H26) and exports (+158% y/y). With raw material prices largely locked in for 2H26, we believe Geely should be able to contain most cost pressures and sustain sequential margin improvement.
Exports target lifted but still too prudent. Management raised its full-year exports guidance to 920k during the results briefing (from 640k in early 2026). However, with 7M26 exports already reaching c.580k units and monthly exports exceeding 100k units in each of the past two months, we believe the revised target remains overly too conservative. Export momentum should also continue to strengthen as Geely expands its overseas product offering across a broader range of price points, while Zeekr accelerates the rollout of higher-end models including the 9X and 8X. Based on the current trajectory, we project Geely to reach c.1.1mn export units in 2026, c.20% above management’s revised target.
Managerial changes but limited impact in our view. Geely announced a major management reshuffle, with Li Shufu stepping down as Chairman of Geely Auto (175 HK) and An Conghui taking over the role, alongside a transition in the CEO position. However, we do not view the change as a meaningful shift in strategic direction, with Li Shufu remains as the Chairman of Geely Holding (the parent company of 175 HK), and will also serve as Lifetime Honorary Chairman of Geely Auto. We believe this reflects more a reduction in Li Shufu’s involvement in day-to-day operations and a further institutionalisation of the group’s management structure. In our view, the reshuffle represents another step in Geely’s transition from a founder-led organisation to a more professionally managed global automotive company, with limited near-term impact to Geely’s operations.
BUY with new TP HKD29 (vs prev HKD28). We raised our FY26F earnings by 3% to factor in the stronger exports sales. We raise TP to HKD29, based on 11x 12-month rolling PE, pegged to 5-year historical average. Currently valuation of 8x rolling PE is attractive. Maintain BUY on Geely given its solid earnings outlook.
1H26 results briefing takeaway
Overseas Expansion & Export Target Outlook. Company raised its 2026 export target to 920k units (from 640k earlier this year) and reiterated its longer-term ambition for two-thirds of sales to come from overseas markets. Rather than pursuing large-scale greenfield investments, company plans to leverage existing capacity within Geely Holding and external partners, sharing manufacturing, supply chains, channels and service networks. Zeekr will also accelerate overseas expansion, with the 9X launching in Q3 and the 8X from Q4, supporting Geely’s push into premium and luxury segments.
Governance Transition & Organisational Setup. Geely announced a significant management reshuffle aimed at strengthening professional and institutionalised governance. Li Shufu will step down as Chairman of Geely Auto while remaining Chairman of parent Geely Holding and becoming Lifetime Honorary Chairman of Geely Auto. An Conghui will assume the Chairmanship, alongside a CEO transition to the next generation of management. Under the “One Geely” strategy, Geely Holding may also inject strategically valuable businesses into Geely Auto over time, with batteries, electric drives and automotive electronics highlighted as key capabilities, although no timetable was provided.
“One Geely” Brand & Product Portfolio Roadmap. Geely has already reduced its product portfolio by more than 20% to minimise overlap and sharpen brand positioning. Galaxy will focus on high-value mainstream products, Lynk & Co on sporty and differentiated offerings, and Zeekr on technology-driven premium and luxury vehicles. Management also acknowledged a gap in competitive mid-tier products between Zeekr and Geely’s higher-volume entry models, which it sees as a key area for improvement. Several new models across Lynk & Co, Galaxy and Zeekr are scheduled for 2H26.
Technology Pipeline & Long-Term Strategic Timeline. Geely will continue prioritising its “full-domain AI” strategy across intelligent driving, smart cockpits, electrification and energy management. Key initiatives include further upgrades to Qianli Haohan, deeper cockpit-driving integration and fifth-generation ultra-fast charging with AI-based thermal management and battery monitoring. Geely will also stop developing conventional ICE-only vehicles and progressively migrate China Star toward I-HAVE hybrid technology, with overseas rollout beginning next year. A more detailed 2030 strategy briefing is planned around year-end.
Q&A
Q1: What kind of overseas customer feedback have the Zeekr 9X and 8X received, and what are the expected sales volumes domestically and internationally?
A1: Overseas interest is strong, particularly in the Middle East and Europe, with some customers importing cars before formal launches. The 9X will launch overseas from 3Q26 and the 8X from 4Q26. Expects Zeekr exports to exceed 80k units in 2026 (vs 42k in 1H26).
Q2: What is the product and technical roadmap for China Star, and will Geely migrate onto the I-HEV hybrid platform?
A2: We will stop developing conventional ICE-only vehicles, with China Star progressively shifting to I-HEV. Several I-HEV models will launch domestically in 2H26, followed by broader overseas rollout from 2027. We expect better fuel economy and performance versus traditional hybrids.
Q3: What are the key strengths and challenges of Geely's global shared-capacity model?
A3: Three key advantages are higher quality, faster localisation and lower investment risk. We will utilise capacity within Geely Holding and external partners while sharing supply chains, channels and service networks. The key execution challenge is coordinating multiple brands and partners effectively.
Q4: Given rising raw-material costs, what is Geely's gross-margin outlook, and what is the BEV launch cadence?
A4: We have mitigated cost pressure through advance inventory and supplier price lock-ins. With a stronger export and premium mix, we expect 3Q26 gross margin to be no worse than 2Q26. Several new BEVs across Galaxy, Lynk & Co and Zeekr will launch in 2H26.
Q5: Will Ford use Geely-developed platforms at its Spanish plant, and what is the trade-payables outlook?
A5: The Ford cooperation will use Geely's GEA base architecture, with European production serving Europe only. Trade payables rose modestly to RMB84bn from RMB81bn, while payable turnover improved to 103 days in 1H26 and 96 days in 2Q26, with further improvement expected.
Q6: What are Geely's plans for charging-network build-out and charging technology?
A6: Management focused mainly on charging technology rather than network or partnership targets. Geely is moving toward MW-level charging, with its fifth-generation system using AI thermal management and battery monitoring to improve charging speed while protecting battery safety and longevity. More details are due next month.
Q7: Will Geely streamline its product portfolio under the “One Geely” strategy?
A7: Yes. Geely has already cut its product portfolio by more than 20% to reduce overlap and sharpen brand positioning. Management also acknowledged a gap in stronger mid-tier blockbuster models and will prioritise filling this segment going forward.

Access more at DBS Insights Direct
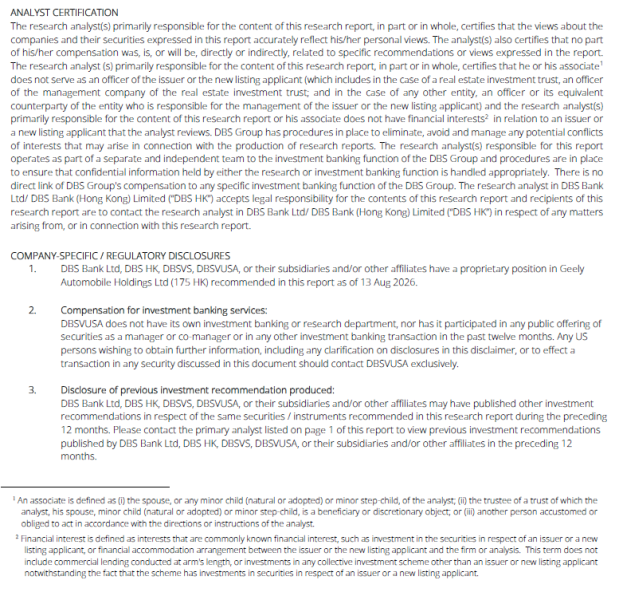
GENERAL DISCLOSURE/DISCLAIMER
This report is prepared by DBS Bank (Hong Kong) Limited (“DBS HK”). This report is solely intended for the clients of DBS Bank Ltd., DBS HK, DBS Vickers (Hong Kong) Limited (“DBSV HK”), and DBS Vickers Securities (Singapore) Pte Ltd. (“DBSVS”), its respective connected and associated corporations and affiliates only and no part of this document may be (i) copied, photocopied or duplicated in any form or by any means or (ii) redistributed without the prior written consent of DBS HK.
The research set out in this report is based on information obtained from sources believed to be reliable, but we (which collectively refers to DBS Bank Ltd., DBS HK, DBSV HK, DBSVS, its respective connected and associated corporations, affiliates and their respective directors, officers, employees and agents (collectively, the “DBS Group”) have not conducted due diligence on any of the companies, verified any information or sources or taken into account any other factors which we may consider to be relevant or appropriate in preparing the research. Accordingly, we do not make any representation or warranty as to the accuracy, completeness or correctness of the research set out in this report. Opinions expressed are subject to change without notice. This research is prepared for general circulation. Any recommendation contained in this document does not have regard to the specific investment objectives, financial situation and the particular needs of any specific addressee. This document is for the information of addressees only and is not to be taken in substitution for the exercise of judgement by addressees, who should obtain separate independent legal or financial advice. The DBS Group accepts no liability whatsoever for any direct, indirect and/or consequential loss (including any claims for loss of profit) arising from any use of and/or reliance upon this document and/or further communication given in relation to this document. This document is not to be construed as an offer or a solicitation of an offer to buy or sell any securities. The DBS Group, along with its affiliates and/or persons associated with any of them may from time to time have interests in the securities mentioned in this document. The DBS Group, may have positions in, and may effect transactions in securities mentioned herein and may also perform or seek to perform broking, investment banking and other banking services for these companies.
Any valuations, opinions, estimates, forecasts, ratings or risk assessments herein constitutes a judgment as of the date of this report, and there can be no assurance that future results or events will be consistent with any such valuations, opinions, estimates, forecasts, ratings or risk assessments. The information in this document is subject to change without notice, its accuracy is not guaranteed, it may be incomplete or condensed, it may not contain all material information concerning the company (or companies) referred to in this report and the DBS Group is under no obligation to update the information in this report.
This publication has not been reviewed or authorized by any regulatory authority in Singapore, Hong Kong or elsewhere. There is no planned schedule or frequency for updating research publication relating to any issuer.
The valuations, opinions, estimates, forecasts, ratings or risk assessments described in this report were based upon a number of estimates and assumptions and are inherently subject to significant uncertainties and contingencies. It can be expected that one or more of the estimates on which the valuations, opinions, estimates, forecasts, ratings or risk assessments were based will not materialize or will vary significantly from actual results. Therefore, the inclusion of the valuations, opinions, estimates, forecasts, ratings or risk assessments described herein IS NOT TO BE RELIED UPON as a representation and/or warranty by the DBS Group (and/or any persons associated with the aforesaid entities), that:
(a) such valuations, opinions, estimates, forecasts, ratings or risk assessments or their underlying assumptions will be achieved, and
(b) there is any assurance that future results or events will be consistent with any such valuations, opinions, estimates, forecasts, ratings or risk assessments stated therein.
Please contact the primary analyst for valuation methodologies and assumptions associated with the covered companies or price targets.
Any assumptions made in this report that refers to commodities, are for the purposes of making forecasts for the company (or companies) mentioned herein. They are not to be construed as recommendations to trade in the physical commodity or in the futures contract relating to the commodity referred to in this report.
On 3 June 2021, President J. Biden issued Executive Order 14032 (“the EO”), superseding Executive Order 13959 of 12 November 2020. The EO, which takes effect on 2 August 2021, prohibits US persons from investing in publicly traded securities or derivatives thereof from firms listed as Chinese Military-Industrial Complex Companies (“CMICs”). The list of CMICs can be found on the US Department of the Treasury’s website at https://home.treasury.gov/policy-issues/financial-sanctions/consolidated-sanctions-list/ns-cmic-list.
DBS Vickers Securities (USA) Inc (“DBSVUSA”), a US-registered broker-dealer, does not have its own investment banking or research department, has not participated in any public offering of securities as a manager or co-manager or in any other investment banking transaction in the past twelve months and does not engage in market-making.
RESTRICTIONS ON DISTRIBUTION
General | This report is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation. |
Australia | This report is being distributed in Australia by DBS Bank Ltd, DBSVS or DBSV HK. DBS Bank Ltd holds Australian Financial Services Licence no. 475946. DBSVS and DBSV HK are exempted from the requirement to hold an Australian Financial Services Licence under the Corporation Act 2001 (“CA”) in respect of financial services provided to the recipients. Both DBS Bank Ltd and DBSVS are regulated by the Monetary Authority of Singapore under the laws of Singapore, and DBSV HK is regulated by the Hong Kong Securities and Futures Commission under the laws of Hong Kong, which differ from Australian laws. Distribution of this report is intended only for “wholesale investors” within the meaning of the CA. |
Hong Kong | This report is being distributed in Hong Kong by DBS Bank Ltd, DBS Bank (Hong Kong) Limited and DBS Vickers (Hong Kong) Limited, all of which are registered with or licensed by the Hong Kong Securities and Futures Commission to carry out the regulated activity of advising on securities. DBS Bank Ltd., Hong Kong Branch is a limited liability company incorporated in Singapore. For any query regarding the materials herein, please contact Dennis Lam (Reg No. AH8290) at dbsvhk@dbs.com |
Indonesia | This report is being distributed in Indonesia by PT DBS Vickers Sekuritas Indonesia. |
Malaysia | This report is distributed in Malaysia by AllianceDBS Research Sdn Bhd ("ADBSR"). Recipients of this report, received from ADBSR are to contact the undersigned at 603-2604 3333 in respect of any matters arising from or in connection with this report. In addition to the General Disclosure/Disclaimer found at the preceding page, recipients of this report are advised that ADBSR (the preparer of this report), its holding company Alliance Investment Bank Berhad, their respective connected and associated corporations, affiliates, their directors, officers, employees, agents and parties related or associated with any of them may have positions in, and may effect transactions in the securities mentioned herein and may also perform or seek to perform broking, investment banking/corporate advisory and other services for the subject companies. They may also have received compensation and/or seek to obtain compensation for broking, investment banking/corporate advisory and other services from the subject companies. Wong Ming Tek, Executive Director, ADBSR |
Singapore | This report is distributed in Singapore by DBS Bank Ltd (Company Regn. No. 196800306E) or DBSVS (Company Regn No. 198600294G), both of which are Exempt Financial Advisers as defined in the Financial Advisers Act and regulated by the Monetary Authority of Singapore. DBS Bank Ltd and/or DBSVS, may distribute reports produced by its respective foreign entities, affiliates or other foreign research houses pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed in Singapore to a person who is not an Accredited Investor, Expert Investor or an Institutional Investor, DBS Bank Ltd accepts legal responsibility for the contents of the report to such persons only to the extent required by law. Singapore recipients should contact DBS Bank Ltd at 6878 8888 for matters arising from, or in connection with the report. |
Thailand | This report is being distributed in Thailand by DBS Vickers Securities (Thailand) Co Ltd. |
United Kingdom | This report is produced by DBS HK which is regulated by the Hong Kong Monetary Authority This report is disseminated in the United Kingdom by DBS Bank Ltd, London Branch (“DBS UK”). DBS Bank Ltd is regulated by the Monetary Authority of Singapore. DBS UK is authorised by the Prudential Regulation Authority and is subject to regulation by the Financial Conduct Authority and limited regulation by the Prudential Regulation Authority. Details about the extent of our regulation by the Prudential Regulation Authority are available from us on request. In respect of the United Kingdom, this report is solely intended for the clients of DBS UK, its respective connected and associated corporations and affiliates only and no part of this document may be (i) copied, photocopied or duplicated in any form or by any means or (ii) redistributed without the prior written consent of DBS UK. This communication is directed at persons having professional experience in matters relating to investments. Any investment activity following from this communication will only be engaged in with such persons. Persons who do not have professional experience in matters relating to investments should not rely on this communication. |
Dubai International Financial Centre | This communication is provided to you as a Professional Client or Market Counterparty as defined in the DFSA Rulebook Conduct of Business Module (the "COB Module"), and should not be relied upon or acted on by any person which does not meet the criteria to be classified as a Professional Client or Market Counterparty under the DFSA rules. This communication is from the branch of DBS Bank Ltd operating in the Dubai International Financial Centre (the "DIFC") under the trading name "DBS Bank Ltd. (DIFC Branch)" ("DBS DIFC"), registered with the DIFC Registrar of Companies under number 156 and having its registered office at units 608 - 610, 6th Floor, Gate Precinct Building 5, PO Box 506538, DIFC, Dubai, United Arab Emirates. DBS DIFC is regulated by the Dubai Financial Services Authority (the "DFSA") with a DFSA reference number F000164. For more information on DBS DIFC and its affiliates, please see http://www.dbs.com/ae/our--network/default.page. Where this communication contains a research report, this research report is prepared by the entity referred to therein, which may be DBS Bank Ltd or a third party, and is provided to you by DBS DIFC. The research report has not been reviewed or authorised by the DFSA. Such research report is distributed on the express understanding that, whilst the information contained within is believed to be reliable, the information has not been independently verified by DBS DIFC. Unless otherwise indicated, this communication does not constitute an "Offer of Securities to the Public" as defined under Article 12 of the Markets Law (DIFC Law No.1 of 2012) or an "Offer of a Unit of a Fund" as defined under Article 19(2) of the Collective Investment Law (DIFC Law No.2 of 2010). The DFSA has no responsibility for reviewing or verifying this communication or any associated documents in connection with this investment and it is not subject to any form of regulation or approval by the DFSA. Accordingly, the DFSA has not approved this communication or any other associated documents in connection with this investment nor taken any steps to verify the information set out in this communication or any associated documents, and has no responsibility for them. The DFSA has not assessed the suitability of any investments to which the communication relates and, in respect of any Islamic investments (or other investments identified to be Shari'a compliant), neither we nor the DFSA has determined whether they are Shari'a compliant in any way. Any investments which this communication relates to may be illiquid and/or subject to restrictions on their resale. Prospective purchasers should conduct their own due diligence on any investments. If you do not understand the contents of this document you should consult an authorised financial adviser. |
United States | This report was prepared by DBS HK. DBSVUSA did not participate in its preparation. The research analyst(s) named on this report are not registered as research analysts with FINRA and are not associated persons of DBSVUSA. The research analyst(s) are not subject to FINRA Rule 2241 restrictions on analyst compensation, communications with a subject company, public appearances and trading securities held by a research analyst. This report is being distributed in the United States by DBSVUSA, which accepts responsibility for its contents. This report may only be distributed to Major U.S. Institutional Investors (as defined in SEC Rule 15a-6) and to such other institutional investors and qualified persons as DBSVUSA may authorize. Any U.S. person receiving this report who wishes to effect transactions in any securities referred to herein should contact DBSVUSA directly and not its affiliate. |
Other jurisdictions | In any other jurisdictions, except if otherwise restricted by laws or regulations, this report is intended only for qualified, professional, institutional or sophisticated investors as defined in the laws and regulations of such jurisdictions. |
HONG KONG DBS Bank (Hong Kong) Ltd Contact: Dennis Lam 13th Floor One Island East, 18 Westlands Road, Quarry Bay, Hong Kong Tel: 852 3668 4181 Fax: 852 2521 1812 e-mail: dbsvhk@dbs.com
| SINGAPORE DBS Bank Ltd Contact: Paul Yong 12 Marina Boulevard, Marina Bay Financial Centre Tower 3 Singapore 018982 Tel: 65 6878 8888 Fax: 65 65353 418 e-mail: groupresearch@dbs.com Company Regn. No. 196800306E |
THAILAND DBS Vickers Securities (Thailand) Co Ltd Contact: Chanpen Sirithanarattanakul 989 Siam Piwat Tower Building, 14th-15th Floor Rama 1 Road, Pathumwan, Bangkok Thailand 10330 Tel. 66 2 857 7831 Fax: 66 2 658 1269 e-mail: DBSVTresearch@dbs.com Company Regn. No 0105539127012 Securities and Exchange Commission, Thailand | INDONESIA PT DBS Vickers Sekuritas (Indonesia) Contact: Maynard Priajaya Arif DBS Bank Tower Ciputra World 1, 32/F Jl. Prof. Dr. Satrio Kav. 3-5 Jakarta 12940, Indonesia Tel: 62 21 3003 4900 Fax: 6221 3003 4943 e-mail: indonesiaresearch@dbs.com
|
|
|