Swire Properties Ltd - Core operations showing improving signs


- Retail tenant sales growth accelerating
- Luxury home sales show strong gains
- Continued capital recycling
- BUY with higher TP of HKD30.38
Pacific Place portfolio outperformed Taikoo Place counterparts. Overall occupancy of the Hong Kong office portfolio, excluding Two Taikoo Place and Six Pacific Place, retreated slightly to 91% in Dec-25 from 92% in Sep-25, primarily due to slightly lower occupancy at Taikoo Place. Office occupancy at Pacific Place stood firm at 96% in Dec-25. Spot rents for One/Two Pacific Place, Three Pacific Place, and One Island East/One Taikoo Place remained stable at HKD85-95psf, HKD80-90psf, and HKD50-65psf, respectively. Rental reversionary growth for the Pacific Place and Taikoo Place portfolios was negative at 13% and 15% in 2025, respectively. In China, occupancy at One INDIGO in Beijing improved to 93% in Dec-25 from 89% in Sep-25. Taikoo Hui Offices and HKRI Centre 1 & Centre 2 reported stable occupancies of 90% and 93% in Dec-25, respectively.
Retail tenant sales growth gaining momentum. The Mall, Pacific Place, and Cityplaza recorded sales growth of 5.6% and 2.7% in 2025 compared to 1.4% and 2% in 1H25. Sales at Citygate Outlets grew by 1.6% in 2025, a turnaround from a decline of 3.3% in 1H25. All three malls outperformed the broader retail market, which registered 1% sales growth in 2025. Asset-enhancement initiatives fuelled outperformance at Taikoo Li Sanlitun in Beijing and HKRI Taikoo Hui in Shanghai, both of which registered solid sales growth of 11.2% and 49.6% in 2025, respectively (1H25: 6.8% and 13.5%). Tenant sales at other malls in China also gained momentum, increasing by 1.6% to 6.9% in 2025, compared with a range of -2.1% to +4.0% growth in 1H25.
The Headland Residences sales update. Swire Properties launched The Headland Residences Phase 1 in Chai Wan for pre-sale in Sep-25 and has since sold 128 units, generating proceeds of >HKD1.1bn, at an average of c.HKD17,000psf. This represents 22% of the total 592 units in Ph 1.
The Headland Residences, redeveloped from the former China Motor Bus depot, is scheduled for completion from the second half of 2025 onwards. The project, developed in two phases, will comprise 850 units across three residential towers with a total gross floor area of 0.69msf. Pre-sale consent for Ph 2 is currently pending government approval. Swire Properties holds an 80% stake in the redevelopment, with the remaining 20% owned by China Motor Bus. The joint venture acquired the site from China Motor Bus in 2015 for HKD850m and subsequently converted it to residential use following a land premium payment of HKD4.54bn. Including construction and financing costs, we estimate the all-in cost at approximately HKD16,500psf on a saleable area basis. As such, the development is expected to be only marginally profitable.
Continued capital recycling to power long-term growth. In Oct-25, Swire Properties offered car park spaces at Taikoo Shing Ph 10 for sale. To date, the company has sold > 400 spaces, generating total proceeds of HKD500m. Separately, the company sold an industrial property in Tsing Yi for HKD750m. This divestment not only enhances bottom-line earnings but also facilitates capital recycling for new investments.
Decent gains from luxury home sales. In Dec-25, Swire Properties agreed to sell 6 Deep Water Bay Road in Island South for HKD2.2bn or HKD147,010psf. Redeveloped from the former rental property Rocky Bank, the site comprises two three-storey houses on a single lot, with saleable areas of approximately 9,600sf and 5,300sf. The transaction is expected to close in 1Q26, and we forecast the disposal to generate pre-tax earnings of over HKD1bn for Swire Properties.
BUY with HKD30.38 TP. Over the past three months, shares of Swire Properties appreciated 10%, underperforming most other landlords. Meanwhile, the stock is trading at a 50% discount to our appraised current NAV, against its 10-year average of 53%. The Pacific Place office portfolio shows signs of stabilisation. This, coupled with improving tenant sales momentum in its Hong Kong and China retail portfolios, should augur well for its rental income in the medium term. Portfolio expansion in China should provide additional growth momentum to earnings and dividends, which should warrant a higher stock valuation over the long term. Reiterate BUY with TP of HKD30.38, based on target discount of 40% to our Dec-26 NAV estimate.

Access more at DBS Insights Direct
GENERAL DISCLOSURE/DISCLAIMER
This report is prepared by DBS Bank (Hong Kong) Limited (“DBS HK”). This report is solely intended for the clients of DBS Bank Ltd., DBS HK, DBS Vickers (Hong Kong) Limited (“DBSV HK”), and DBS Vickers Securities (Singapore) Pte Ltd. (“DBSVS”), its respective connected and associated corporations and affiliates only and no part of this document may be (i) copied, photocopied or duplicated in any form or by any means or (ii) redistributed without the prior written consent of DBS HK.
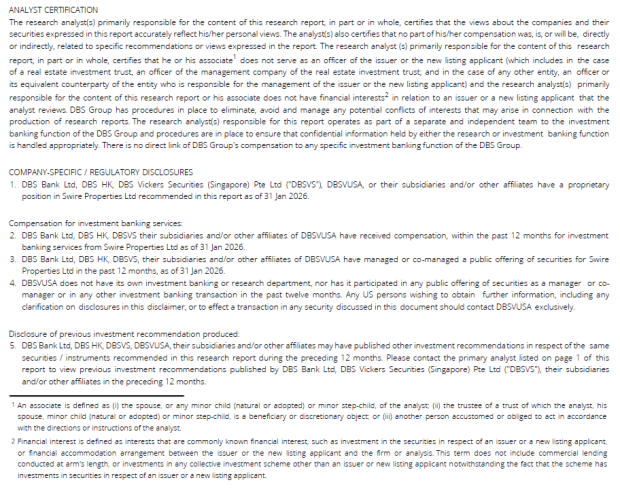
The research set out in this report is based on information obtained from sources believed to be reliable, but we (which collectively refers to DBS Bank Ltd., DBS HK, DBSV HK, DBSVS, its respective connected and associated corporations, affiliates and their respective directors, officers, employees and agents (collectively, the “DBS Group”) have not conducted due diligence on any of the companies, verified any information or sources or taken into account any other factors which we may consider to be relevant or appropriate in preparing the research. Accordingly, we do not make any representation or warranty as to the accuracy, completeness or correctness of the research set out in this report. Opinions expressed are subject to change without notice. This research is prepared for general circulation. Any recommendation contained in this document does not have regard to the specific investment objectives, financial situation and the particular needs of any specific addressee. This document is for the information of addressees only and is not to be taken in substitution for the exercise of judgement by addressees, who should obtain separate independent legal or financial advice. The DBS Group accepts no liability whatsoever for any direct, indirect and/or consequential loss (including any claims for loss of profit) arising from any use of and/or reliance upon this document and/or further communication given in relation to this document. This document is not to be construed as an offer or a solicitation of an offer to buy or sell any securities. The DBS Group, along with its affiliates and/or persons associated with any of them may from time to time have interests in the securities mentioned in this document. The DBS Group, may have positions in, and may effect transactions in securities mentioned herein and may also perform or seek to perform broking, investment banking and other banking services for these companies.
Any valuations, opinions, estimates, forecasts, ratings or risk assessments herein constitutes a judgment as of the date of this report, and there can be no assurance that future results or events will be consistent with any such valuations, opinions, estimates, forecasts, ratings or risk assessments. The information in this document is subject to change without notice, its accuracy is not guaranteed, it may be incomplete or condensed, it may not contain all material information concerning the company (or companies) referred to in this report and the DBS Group is under no obligation to update the information in this report.
This publication has not been reviewed or authorized by any regulatory authority in Singapore, Hong Kong or elsewhere. There is no planned schedule or frequency for updating research publication relating to any issuer.
The valuations, opinions, estimates, forecasts, ratings or risk assessments described in this report were based upon a number of estimates and assumptions and are inherently subject to significant uncertainties and contingencies. It can be expected that one or more of the estimates on which the valuations, opinions, estimates, forecasts, ratings or risk assessments were based will not materialize or will vary significantly from actual results. Therefore, the inclusion of the valuations, opinions, estimates, forecasts, ratings or risk assessments described herein IS NOT TO BE RELIED UPON as a representation and/or warranty by the DBS Group (and/or any persons associated with the aforesaid entities), that:
(a) such valuations, opinions, estimates, forecasts, ratings or risk assessments or their underlying assumptions will be achieved, and
(b) there is any assurance that future results or events will be consistent with any such valuations, opinions, estimates, forecasts, ratings or risk assessments stated therein.
Please contact the primary analyst for valuation methodologies and assumptions associated with the covered companies or price targets.
Any assumptions made in this report that refers to commodities, are for the purposes of making forecasts for the company (or companies) mentioned herein. They are not to be construed as recommendations to trade in the physical commodity or in the futures contract relating to the commodity referred to in this report.
On 3 June 2021, President J. Biden issued Executive Order 14032 (“the EO”), superseding Executive Order 13959 of 12 November 2020. The EO, which takes effect on 2 August 2021, prohibits US persons from investing in publicly traded securities or derivatives thereof from firms listed as Chinese Military-Industrial Complex Companies (“CMICs”). The list of CMICs can be found on the US Department of the Treasury’s website at https://home.treasury.gov/policy-issues/financial-sanctions/consolidated-sanctions-list/ns-cmic-list.
DBS Vickers Securities (USA) Inc (“DBSVUSA”), a US-registered broker-dealer, does not have its own investment banking or research department, has not participated in any public offering of securities as a manager or co-manager or in any other investment banking transaction in the past twelve months and does not engage in market-making.
RESTRICTIONS ON DISTRIBUTION
General | This report is not directed to, or intended for distribution to or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation. |
Australia | This report is being distributed in Australia by DBS Bank Ltd, DBSVS or DBSV HK. DBS Bank Ltd holds Australian Financial Services Licence no. 475946. DBSVS and DBSV HK are exempted from the requirement to hold an Australian Financial Services Licence under the Corporation Act 2001 (“CA”) in respect of financial services provided to the recipients. Both DBS Bank Ltd and DBSVS are regulated by the Monetary Authority of Singapore under the laws of Singapore, and DBSV HK is regulated by the Hong Kong Securities and Futures Commission under the laws of Hong Kong, which differ from Australian laws. Distribution of this report is intended only for “wholesale investors” within the meaning of the CA. |
Hong Kong | This report is being distributed in Hong Kong by DBS Bank Ltd, DBS Bank (Hong Kong) Limited and DBS Vickers (Hong Kong) Limited, all of which are registered with or licensed by the Hong Kong Securities and Futures Commission to carry out the regulated activity of advising on securities. DBS Bank Ltd., Hong Kong Branch is a limited liability company incorporated in Singapore. For any query regarding the materials herein, please contact Dennis Lam (Reg No. AH8290) at dbsvhk@dbs.com |
Indonesia | This report is being distributed in Indonesia by PT DBS Vickers Sekuritas Indonesia. |
Malaysia | This report is distributed in Malaysia by AllianceDBS Research Sdn Bhd ("ADBSR"). Recipients of this report, received from ADBSR are to contact the undersigned at 603-2604 3333 in respect of any matters arising from or in connection with this report. In addition to the General Disclosure/Disclaimer found at the preceding page, recipients of this report are advised that ADBSR (the preparer of this report), its holding company Alliance Investment Bank Berhad, their respective connected and associated corporations, affiliates, their directors, officers, employees, agents and parties related or associated with any of them may have positions in, and may effect transactions in the securities mentioned herein and may also perform or seek to perform broking, investment banking/corporate advisory and other services for the subject companies. They may also have received compensation and/or seek to obtain compensation for broking, investment banking/corporate advisory and other services from the subject companies. Wong Ming Tek, Executive Director, ADBSR |
Singapore | This report is distributed in Singapore by DBS Bank Ltd (Company Regn. No. 196800306E) or DBSVS (Company Regn No. 198600294G), both of which are Exempt Financial Advisers as defined in the Financial Advisers Act and regulated by the Monetary Authority of Singapore. DBS Bank Ltd and/or DBSVS, may distribute reports produced by its respective foreign entities, affiliates or other foreign research houses pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed in Singapore to a person who is not an Accredited Investor, Expert Investor or an Institutional Investor, DBS Bank Ltd accepts legal responsibility for the contents of the report to such persons only to the extent required by law. Singapore recipients should contact DBS Bank Ltd at 6878 8888 for matters arising from, or in connection with the report. |
Thailand | This report is being distributed in Thailand by DBS Vickers Securities (Thailand) Co Ltd. |
United Kingdom | This report is produced by DBS HK which is regulated by the Hong Kong Monetary Authority This report is disseminated in the United Kingdom by DBS Bank Ltd, London Branch (“DBS UK”). DBS Bank Ltd is regulated by the Monetary Authority of Singapore. DBS UK is authorised by the Prudential Regulation Authority and is subject to regulation by the Financial Conduct Authority and limited regulation by the Prudential Regulation Authority. Details about the extent of our regulation by the Prudential Regulation Authority are available from us on request. In respect of the United Kingdom, this report is solely intended for the clients of DBS UK, its respective connected and associated corporations and affiliates only and no part of this document may be (i) copied, photocopied or duplicated in any form or by any means or (ii) redistributed without the prior written consent of DBS UK. This communication is directed at persons having professional experience in matters relating to investments. Any investment activity following from this communication will only be engaged in with such persons. Persons who do not have professional experience in matters relating to investments should not rely on this communication. |
Dubai International Financial Centre | This communication is provided to you as a Professional Client or Market Counterparty as defined in the DFSA Rulebook Conduct of Business Module (the "COB Module"), and should not be relied upon or acted on by any person which does not meet the criteria to be classified as a Professional Client or Market Counterparty under the DFSA rules. This communication is from the branch of DBS Bank Ltd operating in the Dubai International Financial Centre (the "DIFC") under the trading name "DBS Bank Ltd. (DIFC Branch)" ("DBS DIFC"), registered with the DIFC Registrar of Companies under number 156 and having its registered office at units 608 - 610, 6th Floor, Gate Precinct Building 5, PO Box 506538, DIFC, Dubai, United Arab Emirates. DBS DIFC is regulated by the Dubai Financial Services Authority (the "DFSA") with a DFSA reference number F000164. For more information on DBS DIFC and its affiliates, please see http://www.dbs.com/ae/our--network/default.page. Where this communication contains a research report, this research report is prepared by the entity referred to therein, which may be DBS Bank Ltd or a third party, and is provided to you by DBS DIFC. The research report has not been reviewed or authorised by the DFSA. Such research report is distributed on the express understanding that, whilst the information contained within is believed to be reliable, the information has not been independently verified by DBS DIFC. Unless otherwise indicated, this communication does not constitute an "Offer of Securities to the Public" as defined under Article 12 of the Markets Law (DIFC Law No.1 of 2012) or an "Offer of a Unit of a Fund" as defined under Article 19(2) of the Collective Investment Law (DIFC Law No.2 of 2010). The DFSA has no responsibility for reviewing or verifying this communication or any associated documents in connection with this investment and it is not subject to any form of regulation or approval by the DFSA. Accordingly, the DFSA has not approved this communication or any other associated documents in connection with this investment nor taken any steps to verify the information set out in this communication or any associated documents, and has no responsibility for them. The DFSA has not assessed the suitability of any investments to which the communication relates and, in respect of any Islamic investments (or other investments identified to be Shari'a compliant), neither we nor the DFSA has determined whether they are Shari'a compliant in any way. Any investments which this communication relates to may be illiquid and/or subject to restrictions on their resale. Prospective purchasers should conduct their own due diligence on any investments. If you do not understand the contents of this document you should consult an authorised financial adviser. |
United States | This report was prepared by DBS HK. DBSVUSA did not participate in its preparation. The research analyst(s) named on this report are not registered as research analysts with FINRA and are not associated persons of DBSVUSA. The research analyst(s) are not subject to FINRA Rule 2241 restrictions on analyst compensation, communications with a subject company, public appearances and trading securities held by a research analyst. This report is being distributed in the United States by DBSVUSA, which accepts responsibility for its contents. This report may only be distributed to Major U.S. Institutional Investors (as defined in SEC Rule 15a-6) and to such other institutional investors and qualified persons as DBSVUSA may authorize. Any U.S. person receiving this report who wishes to effect transactions in any securities referred to herein should contact DBSVUSA directly and not its affiliate. |
Other jurisdictions | In any other jurisdictions, except if otherwise restricted by laws or regulations, this report is intended only for qualified, professional, institutional or sophisticated investors as defined in the laws and regulations of such jurisdictions. |
HONG KONG DBS Bank (Hong Kong) Ltd Contact: Dennis Lam 13th Floor One Island East, 18 Westlands Road, Quarry Bay, Hong Kong Tel: 852 3668 4181 Fax: 852 2521 1812 e-mail: dbsvhk@dbs.com
| SINGAPORE DBS Bank Ltd Contact: Paul Yong 12 Marina Boulevard, Marina Bay Financial Centre Tower 3 Singapore 018982 Tel: 65 6878 8888 Fax: 65 65353 418 e-mail: groupresearch@dbs.com Company Regn. No. 196800306E |
THAILAND DBS Vickers Securities (Thailand) Co Ltd Contact: Chanpen Sirithanarattanakul 989 Siam Piwat Tower Building, 14th-15th Floor Rama 1 Road, Pathumwan, Bangkok Thailand 10330 Tel. 66 2 857 7831 Fax: 66 2 658 1269 e-mail: DBSVTresearch@dbs.com Company Regn. No 0105539127012 Securities and Exchange Commission, Thailand | INDONESIA PT DBS Vickers Sekuritas (Indonesia) Contact: Maynard Priajaya Arif DBS Bank Tower Ciputra World 1, 32/F Jl. Prof. Dr. Satrio Kav. 3-5 Jakarta 12940, Indonesia Tel: 62 21 3003 4900 Fax: 6221 3003 4943 e-mail: indonesiaresearch@dbs.com
|
|
|