

- US/Eurozone: Fed Chairman Kevin Warsh’s Jackson Hole keynote speech on Friday remains the most important event this week; the symposium is viewed more as a credibility event rather than a rate-signalling one
- South Korea: BOK raised its policy rate for a second consecutive meeting to 3% as expected, alongside an upgrade in 2026 and 2027 GDP forecast to 3.3% and 2.9%, respectively
- Thailand: We expect BOT to stay on extended pause given the low and uneven pace of economic growth and headline inflation remaining within the central bank’s target range
- India-North Asia: India’s deeper ties with North Asia will mark a step towards technology-focused integration; China, HK, and Japan dominate the region’s trade linkages; Taiwan carries the most potential
Related Insights
US/Eurozone: Will Warsh align with Bessent? Fed Chairman Kevin Warsh’s Jackson Hole keynote speech on Friday, 28 Aug remains the most important event this week. The symposium is viewed more as a credibility event rather than a rate-signalling one. The decline in the 30Y yield over two days (24-25 August) serves only as a reprieve, not a resolution. US Treasury Secretary Scott Bessent’s decision to expand long-bond buybacks seeks to calm markets. Still, it raises questions about the line between liquidity management and the Fed’s monetary policy, complicating Warsh’s earlier willingness to let markets tighten financial conditions through higher long yields. Overall, Warsh faces a difficult balancing act: defending the Fed’s independence and price-stability mandate while providing greater clarity on the Fed’s reaction function without abandoning his preference for less forward guidance.
Meanwhile, the US Conference Board consumer confidence report was distinctly soft. The headline index fell to 89.4 in August, below the 90.2 consensus and July’s downwardly revised reading of 90.2 (from 90.8). US consumers turned more cautious following the surprise decline in July’s retail sales. They were also less confident about future employment prospects, consistent with July’s negative nonfarm payrolls.
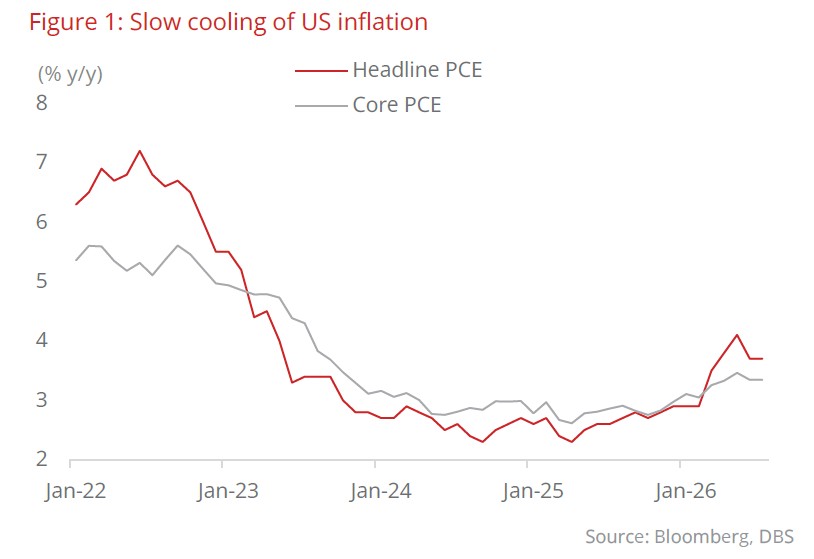
US core PCE inflation, released 26 Aug, rose 0.2% m/m and 3.3% y/y in July, matching market expectations, whilst headline PCE inflation came in firmer than expected at 0.2% m/m and 3.7% y/y (consensus: 0.1% and 3.6%). Second reading on US GDP remained unchanged at 1.5% q/q annualised growth while consumer spending stalled in July with 0.0% m/m real personal spending. That said, markets continue to fully price in a Fed rate hike of 25 bps by December, while we expect no rate hike through the remainder of this year.
For Eurozone, Germany's economy grew at 0.3% q/q in 2Q26, faster than initially indicated (0.2%). Its leading indicator, the ifo Business Climate index, rose for a fourth consecutive month to 88.8 in August from July’s 86.7, posting the highest figure since Aug 2025. Both the current assessment and expectations improved significantly. The data suggests Germany’s economy is weathering tariffs, geopolitical tensions, and the energy shock better than expected, although the downside risks remain on persistently elevated oil and gas prices.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.