

Related Insights
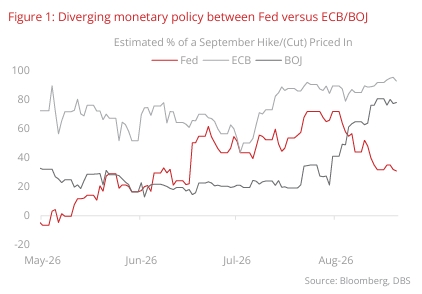
G3: Policy divergence between the Fed and BOJ/ECB. Markets expect policy divergence between the Fed and ECB/BOJ in September. With a series of muted data prints from the US over the past few weeks, investors are paring Fed hike expectations. By contrast, pricing for further tightening by the BOJ and ECB has firmed up. The odds of BOJ’s September hike are now hovering close to 80%. Similarly, the market is assigning 90% odds of an ECB hike in September. It is interesting that inflation breakevens are higher now compared to three months ago for Japan and Germany (in contrast to the US). This could be a factor explaining why the ECB and BOJ are keeping to a tightening stance despite the fall off in oil prices.
For Japan, we revised our 2026 and 2027 GDP growth forecasts to 0.9% and 1.0%, respectively, from 0.5% and 0.5% previously. Our CPI inflation forecast is maintained at 1.8% for 2026 but revised down to 1.5% for 2027. The 2Q26 GDP data released on 17 August, while lower than consensus, was in line with our expectations at 1.1% q/q saar. The 1.1% growth followed a strong 1.9% expansion in 1Q26 and remained broadly in line with Japan’s average growth rate over the past five years. Our annual forecast revisions, to a large extent, take into account the government’s recent approval to cut the food consumption tax from 8% to 1%, effective from April 2027. Food has a large weight in Japan’s CPI, and reducing the tax rate on food products to 1% is estimated to lower 2027 CPI inflation by a significant 1% pts. Given that food is a daily necessity and a substantial portion of the tax savings is likely to be saved, we estimate that the boost to 2027 GDP growth will be modest, at around 0.2% pts.
We expect the BOJ to accelerate the pace of rate hikes to 25bps every 3-4 months, from once every 6 months previously, with a higher terminal rate of 1.75% in the current tightening cycle. We bring forward our expected timing of the next BOJ rate hike to September and expect two further moves in 1Q27 and 2Q27, respectively, taking the overnight call rate to 1.75% by mid-2027. The latest BOJ communication has become more hawkish, while the government also appears less opposed to an early hike, further increasing the likelihood of a September move. Various measures suggest that underlying inflation has reached a stable 1.5-2.0% range (CPI excluding fresh food, energy, and institutional factors: 2.0%; trimmed-mean CPI: 1.6%), pointing to a neutral interest rate of around 2%.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.