- World Cup drove strong volume growth for sponsors in beverage categories
- FY26 guidance was largely reaffirmed, with spirits companies remaining the key growth laggard amid US and China industry headwinds
- India listings remain a key value-unlock catalyst for select beverage players
Related Insights
2Q26 earnings were mixed across beverage players, with companies better able to leverage World Cup activations outperforming. Notably, Coca-Cola and AB InBev both delivered revenue and earnings beats. As the official beverage and beer sponsors of the World Cup respectively, both companies executed consumer activations effectively, driving strong volume growth. Coca-Cola reported 5% volume growth for its trademark Coca-Cola, its strongest performance in 17 years excluding Covid recovery periods. Similarly, AB InBev estimated that the World Cup remains on track to contribute approximately 25 bps of full year volume uplift. In contrast, while PepsiCo’s Frito-Lay was the official World Cup snack food sponsor, it delivered flattish volume growth, which management attributed to a challenging consumer environment due to high gasoline prices and delays in pricing investments.
Execution remains key, with most beverage companies under our coverage largely reaffirming their FY26 revenue and earnings guidance. Coca-Cola was the notable exception, raising its outlook on the back of strong volume momentum, which we attribute to successful World Cup activations and its ability to stay closely connected with local consumers through effective product innovation. In contrast, while PepsiCo’s affordability pivot is a step in the right direction, its products appear to be resonating less effectively with consumers, as reflected in continued weakness in North America sales volumes. Although PepsiCo maintained its guidance, management cautioned that earnings could land at the lower end of the range as it increases marketing investments in North America to support volume growth. Pernod Ricard also stood out, guiding for a 3% to 4% decline in organic sales for FY26, broadly in line with its peer Diageo’s 2% reported decline, highlighting the ongoing challenges facing the premium spirits category, particularly in the US and China.
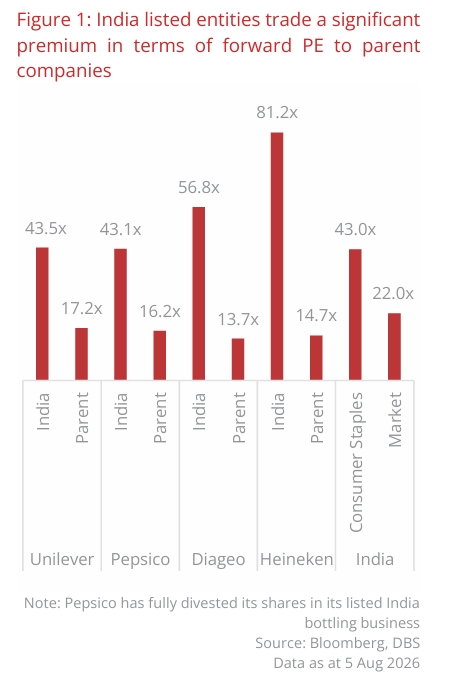
Looking to unlock value through the listing of Indian subsidiaries. Indian consumer staples companies trade at forward P/E multiples that are 2.5x to 5.5x higher than those of their parent companies or global brand owners. Beyond earnings delivery, several beverage players, including Coca-Cola, Carlsberg, and Pernod Ricard, are exploring listings of their Indian operations to capitalise on these attractive valuations. In addition to raising funds to strengthen their capital structure, an India listing could help streamline operations. For Coca-Cola, this would allow the company to sharpen its focus on its higher-margin brands and concentrate on its core business.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.