

- Gold’s correction appears to be maturing, with inflation, rate, and positioning pressures easing after six months of tactical de-risking
- Energy market adaptation is reducing worst-case inflation risks from the US-Iran conflict, lowering pressure for extreme monetary tightening
- Asian buyers are providing visible support near USD4,000/oz., reinforcing the region’s growing role in gold price discovery
- China’s restrictions on leveraged retail trading may curb speculative fragility and improve the quality of gold demand
- Strategic allocations of 5–10% can enhance portfolio resilience, diversification, and wealth preservation without materially altering balanced portfolios
Related Insights
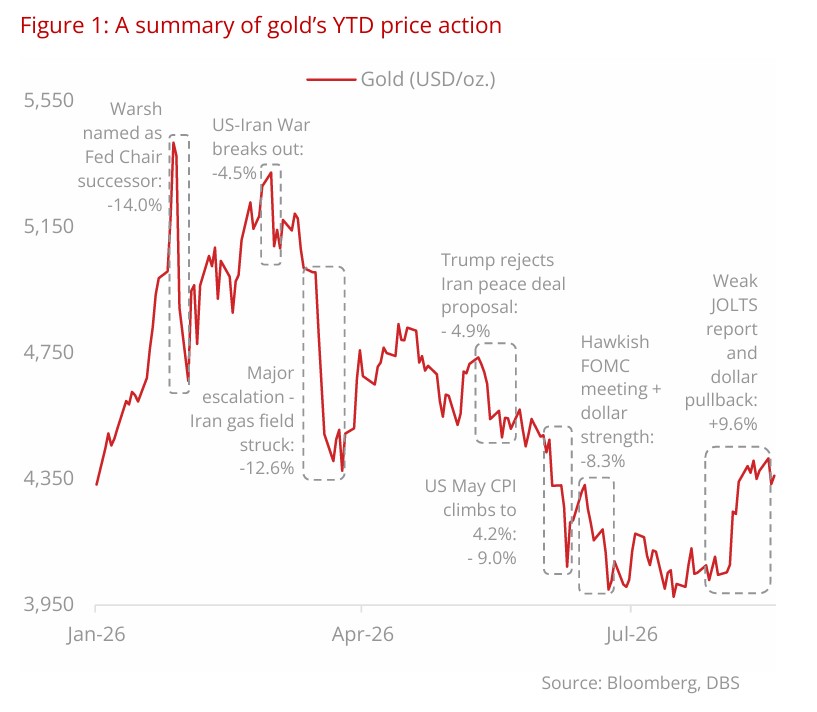
Gold has been under pressure from inflation and rate worries this year. Gold has faced persistent tactical pressure as inflation and rate risks have intensified. The first major sell-off came in January, when Warsh was cited as a potential successor to Powell as Fed Chair, prompting markets to price in the possibility of a more hawkish policy stance. The US-Iran conflict then drove energy prices higher, deepening inflation concerns and reinforcing the hawkish Fed narrative. Against this backdrop, gold prices have trended lower over the past six months.
However, we believe the correction is maturing. Gold may be turning a corner as the pressures behind the sell-off are becoming less acute. Firstly, adaptation in energy markets is helping to curb macro risks from inflation. Secondly, robust demand is emerging for gold at around the USD4,000/oz. level, especially from Asian investors. Thirdly, restrictions on leveraged retail gold trading in China have helped to stem some of the speculative flows within the asset class. Lastly, spiking long-end government bond yields suggest a potential revival of gold as a monetary debasement hedge.
Strategic role as portfolio risk diversifier remains intact. From a longer-term perspective, gold remains strategically important irrespective of the next price catalyst. Its value, from a portfolio construction perspective, comes from diversification, liquidity, and wealth preservation. Investors should therefore treat present price weakness as an opportunity to rebuild or maintain a strategic gold allocation in their portfolios rather than attempting to trade every change in the geopolitical and rates outlook.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.