


Related insights
- Rates: Waiting for the Fed to follow through14 Sep 2026
- Research Library14 Sep 2026
- Macro Insights Weekly: USD-UST Tension14 Sep 2026
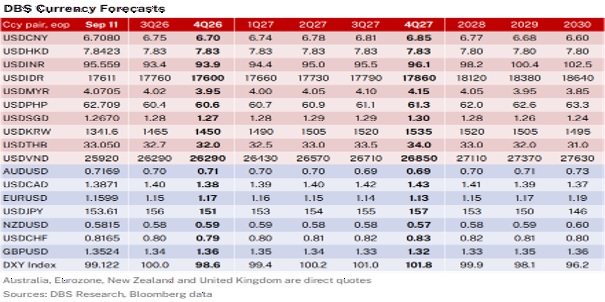
The EUR has a subtle advantage over the USD this week. Last week’s governing council meeting reinforced the European Central Bank’s willingness to deliver the monetary policy needed to return inflation to target. Despite two hikes in June and September, the EUR-positive case is less about the ECB’s hawkishness than its institutional credibility. Faced with resurgent oil prices, the ECB has prioritized above-target inflation over the risks to a resilient Eurozone economy. Fiscal concerns remain in France and Italy, but the ECB appears less constrained by domestic political considerations.
The contrast with the Fed is becoming hard to ignore. Fed Chairman Kevin Warsh has similarly stressed the need to restore price stability, but his rejection of forward guidance has left markets with less clarity over the Fed’s reaction function. More importantly, monetary policy is increasingly viewed in light of competing pressures from Washington. President Donald Trump wants lower rates ahead of the November midterms, while Treasury Secretary Scott Bessent is trying to contain the rise in long-dated Treasury yields. Hence, a hawkish Fed is no longer unambiguously USD-positive.
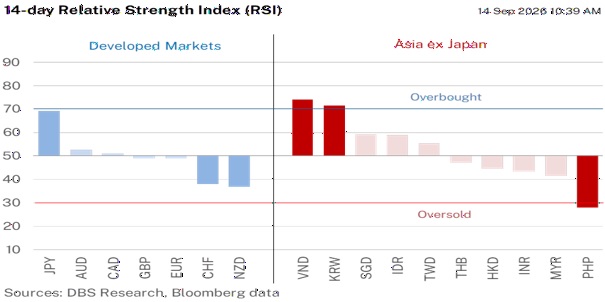
If the EUR has a credibility advantage, the JPY has a policy-regime change advantage. Speculators have unwound their short JPY positions following July’s joint US-Japan currency intervention and a shift in expectations towards further Bank of Japan tightening. Bessent also helped recast “Takaichinomics” away from being Abenomics 2.0, from reflation towards deregulation, investment, and shareholder-friendly structural reform. By implicitly pushing back against Prime Minister Sanae Takaichi’s fiscal instincts, Bessent gave the BOJ greater political room to normalize interest rates. Even former BOJ-tightening sceptics – including Takuji Aida, an economic adviser to Takaichi and a former vocal opponent of BOJ tightening – are now acknowledging the case for higher rates, strengthening expectations for a hawkish hike on September 18.
GBP looks most vulnerable of the three central banks heading into Thursday’s Bank of England meeting. The BOE is widely expected to keep the bank rate unchanged at 3.75%, leaving GBP without the policy support enjoyed by the EUR and JPY. Nevertheless, GBP could find support if the BOE narrows the gap with the ECB and the BOJ in acknowledging the renewed inflation threat posed by higher crude prices. The larger upside risk, however, comes from the Fed. With a US rate hike now heavily discounted, a Fed hold would force a potentially sharp repricing, pulling the USD lower. The market will likely take it upon itself to raise long-dated US Treasury yields to tighten financial conditions.
Quote of the Day
“The rich will do anything for the poor but get off their backs.”
Karl Marx
Today in history
Karl Marx published the first volume of Das Kapital on September 14, 1867, presenting a foundational critique of political economy and the capitalist mode of production.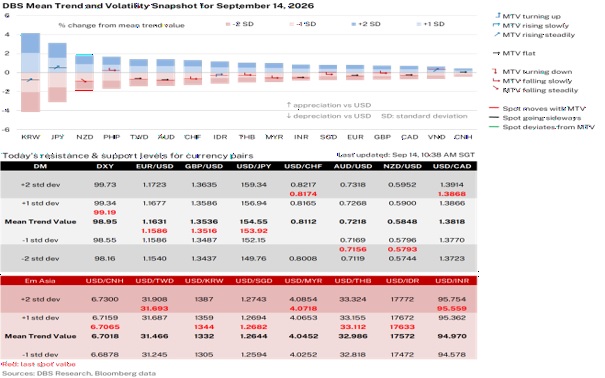

Topic
GENERAL DISCLOSURE/ DISCLAIMER (For Macroeconomics, Currencies, Interest Rates, Digital Assets or Commodities)[1]
The information herein is published by DBS Bank Ltd and/or DBS Bank (Hong Kong) Limited (each and/or collectively, the “Company”). It is based on information obtained from sources believed to be reliable, but the Company does not make any representation or warranty, express or implied, as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions expressed are subject to change without notice. This research is prepared for general circulation. Any recommendation contained herein does not have regard to the specific investment objectives, financial situation and the particular needs of any specific addressee. The information herein is published for the information of addressees only and is not to be taken in substitution for the exercise of judgement by addressees, who should obtain separate legal or financial advice. The Company, or any of its related companies or any individuals connected with the group accepts no liability for any direct, special, indirect, consequential, incidental damages or any other loss or damages of any kind arising from any use of the information herein (including any error, omission or misstatement herein, negligent or otherwise) or further communication thereof, even if the Company or any other person has been advised of the possibility thereof. The information herein is not to be construed as an offer or a solicitation of an offer to buy or sell any securities, futures, options or other financial instruments or to provide any investment advice or services. The Company and its associates, their directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned herein and may also perform or seek to perform broking, investment banking and other banking or financial services for these companies. The information herein is not directed to, or intended for distribution to or use by, any person or entity that is a citizen or resident of or located in any locality, state, country, or other jurisdiction (including but not limited to citizens or residents of the United States of America) where such distribution, publication, availability or use would be contrary to law or regulation. The information is not an offer to sell or the solicitation of an offer to buy any security in any jurisdiction (including but not limited to the United States of America) where such an offer or solicitation would be contrary to law or regulation.
[#for Distribution in Singapore] This report is distributed in Singapore by DBS Bank Ltd (Company Regn. No. 196800306E) which is Exempt Financial Advisers as defined in the Financial Advisers Act and regulated by the Monetary Authority of Singapore. DBS Bank Ltd may distribute reports produced by its respective foreign entities, affiliates or other foreign research houses pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed in Singapore to a person who is not an Accredited Investor, Expert Investor or an Institutional Investor, DBS Bank Ltd accepts legal responsibility for the contents of the report to such persons only to the extent required by law. Singapore recipients should contact DBS Bank Ltd at 65-6878-8888 for matters arising from, or in connection with the report.
DBS Bank Ltd., 12 Marina Boulevard, Marina Bay Financial Centre Tower 3, Singapore 018982. Tel: 65-6878-8888. Company Registration No. 196800306E.
DBS Bank Ltd., Hong Kong Branch, a company incorporated in Singapore with limited liability. 18th Floor, The Center, 99 Queen’s Road Central, Central, Hong Kong SAR.
DBS Bank (Hong Kong) Limited, a company incorporated in Hong Kong with limited liability. 11th Floor, The Center, 99 Queen’s Road Central, Central, Hong Kong SAR.
[1] This disclaimer may not apply if the applicable assets fall within the definition of 'financial instruments' that are set out in Article 2(1) EU MAR (e.g. financial instruments that are traded on a regulated market, MTF or OTF, etc.). Section C of Annex I of MiFID2 specifies these 'financial instruments'.
Related insights
- Rates: Waiting for the Fed to follow through14 Sep 2026
- Research Library14 Sep 2026
- Macro Insights Weekly: USD-UST Tension14 Sep 2026
Related insights
- Rates: Waiting for the Fed to follow through14 Sep 2026
- Research Library14 Sep 2026
- Macro Insights Weekly: USD-UST Tension14 Sep 2026