

- EU car registrations rose 5.7% y/y in 1H26, with Chinese OEMs capturing a disproportionate share of incremental market growth
- BYD, Chery, and Leapmotor accounted for nearly 60% of incremental EU registrations, highlighting accelerating Chinese market share gains across Europe
- Potential tariffs and reduced China export incentives could create near-term headwinds, but are unlikely to reverse structural market share shifts
- European OEMs are responding by rationalising capacity, costs, and production footprints, reflecting intensifying competition and persistent cost disadvantages against Chinese peers
- Favour Chinese over European OEMs, particularly BYD and Geely, supported by stronger cost competitiveness, faster product cycles, and overseas expansion
Related insights
- Research Library16 Oct 2026
- Market volatility and China trade relations 16 Oct 2026
- CNY rates: CNY Appreciation and Excess Savings Fuel Bond Buying 16 Oct 2026
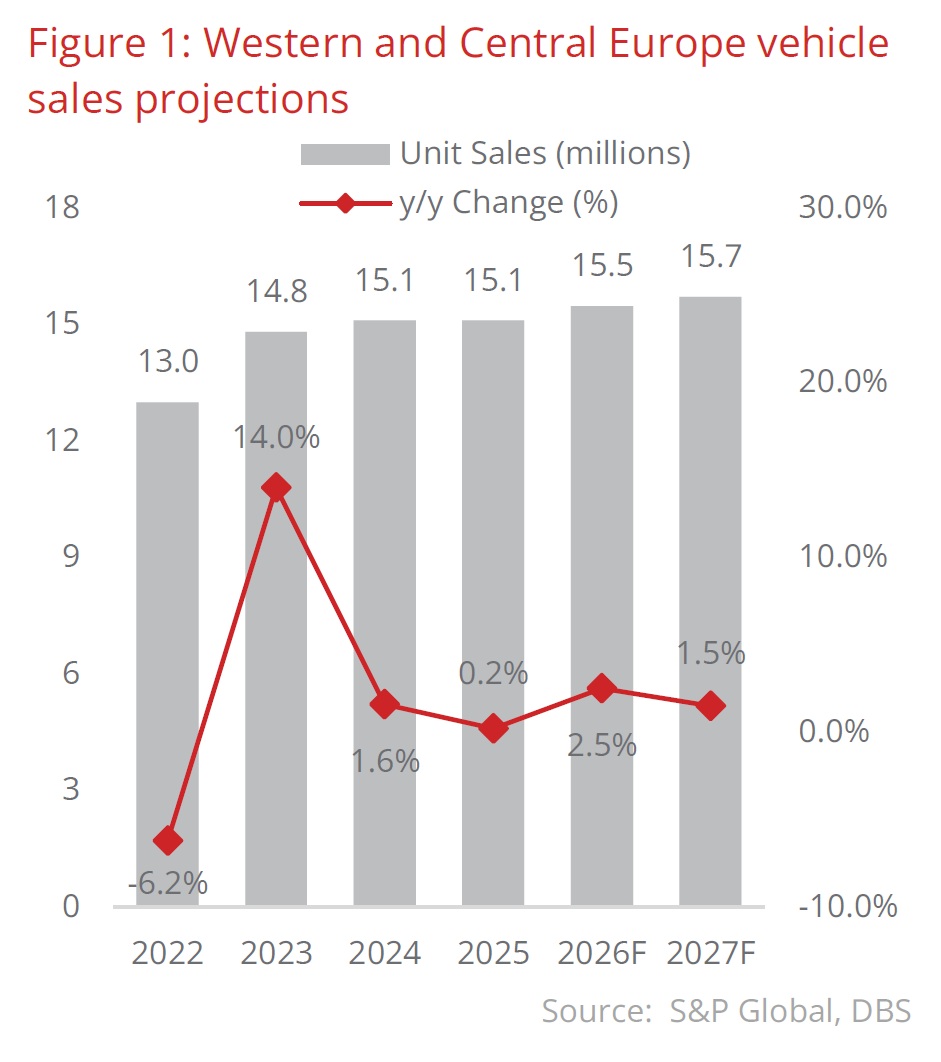
Chinese OEMs capturing a disproportionate share of Europe's recovery. EU new car registrations increased 5.7% y/y to 5.9mn units in 1H26 per ACEA, but much of the incremental growth was captured by Chinese automakers. BYD registrations surged 168% y/y to 131k units, while Chery and Leapmotor grew 269%/527% to 85k/48k units respectively. Together, these three OEMs accounted for nearly 60% of the EU market's incremental registrations during the period, while BYD, SAIC, Chery, and Leapmotor's combined market share doubled to 6.6% from 3.4% a year earlier. In contrast, growth among incumbent European OEMs remained considerably more subdued, with the widening competitive gap increasingly reflected in their strategies to rationalise capacity, costs, and product portfolios.
Trade barriers unlikely to reverse the structural market-share shift. Potential additional trade measures on Chinese vehicles and possible reductions in China's auto export incentives could slow Chinese OEMs' European expansion near term, but we do not expect them to reverse the longer-term trend. Per JATO, Chinese brands continue to offer vehicles at c.9-10% lower average prices than its competitors, alongside competitive technology, specifications, and standard equipment, supported by advantages in supply chains and faster product development. More importantly, European OEMs are increasingly restructuring around a lower-growth environment: Volkswagen estimates >500k units of excess European capacity and plans further rationalisation till 2030, BMW is cutting costs and jobs, while Mercedes is shifting incremental production toward lower-cost Hungary and targeting further German cost reductions. We believe these actions reinforce rather than contradict the structural market-share challenge faced by the EU OEMs.
Prefer Chinese over European OEMs. We believe the widening competitive gap increasingly favours Chinese OEMs, with tariffs potentially moderating the pace of European share gains but unlikely to address the underlying differences in cost, technology, and product development speed. European OEMs face the more difficult task of simultaneously defending domestic market share, restructuring excess or high-cost capacity, and funding their electrification transition, which could constrain margins even as European auto demand recovers. These dynamics increasingly favour Chinese OEMs over their European peers, particularly BYD and Geely. BYD’s vertical integration, manufacturing scale, and an expanding European production footprint, positions it to capitalise on cost and technology advantages, while Geely’s improving overseas momentum, a broad multi-brand portfolio and attractive valuation signals rooms for continued expansion relative to incumbent European producers.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.
Related insights
- Research Library16 Oct 2026
- Market volatility and China trade relations 16 Oct 2026
- CNY rates: CNY Appreciation and Excess Savings Fuel Bond Buying 16 Oct 2026
Related insights
- Research Library16 Oct 2026
- Market volatility and China trade relations 16 Oct 2026
- CNY rates: CNY Appreciation and Excess Savings Fuel Bond Buying 16 Oct 2026