- The global ride-hailing market is expected to grow at a 16.3% CAGR during 2026–2031, reaching USD392bn, supported by rising urban mobility and delivery demand
- Uber’s acquisition of Delivery Hero’s food delivery business reinforces the importance of scale, capital discipline, and consolidation in improving long-term industry profitability
- Uber, Lyft, and Grab all delivered strong 1Q26 profitability, driven by operating leverage, healthy demand growth, and continued execution on cost efficiency
- Uber's larger economic stake in Grab and its non-compete obligations reduce the likelihood of an aggressive Southeast Asia re-entry, supporting rational competition and continued margin expansion for Grab
- We prefer dominant platforms with leading market share, sustainable profitability, and strong execution as industry consolidation increasingly favours scaled operators
Related insights
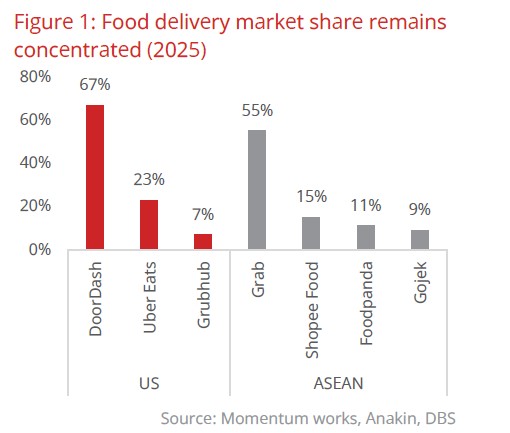
The Uber–Delivery Hero deal highlights the importance of on-the ground density and scale in food delivery. Uber's planned USD14.8bn acquisition of ~80% of Delivery Hero (DHER) expands its footprint to 99 markets. However, DHER's acquired assets generate only a 2.6% EBITDA margin on GMV compared to Uber's more mature delivery economics. This serves as a reminder that in this hyper-local business, density and execution on the ground, rather than market count, determine profitability. Notably, SSW Partners, a financial sponsor, is separately taking DHER's remaining 14 markets private. We view these two outcomes as evidence that the industry is bifurcating. Platforms with genuine, dominant local density (Uber dominates on-demand market share in the US, Canada, UK, Australia; DoorDash in the US, where it holds >65% delivery share) can defend pricing and reinvest in growth. In contrast, sponsor-owned sub-scale players such as those in SSW's carve-out, lack the capacity to compete on anything but price. The implication for investors is that, as more of the delivery "long tail" is absorbed into either camp, promotional intensity should fall structurally, giving industry margins room to expand toward Uber's demonstrated ~4%+ Gross Bookings Value (GBV) delivery margin. This reinforces our preference for platforms with dominant, defensible local density. That said, we caution against overstating the transaction's direct relevance to Southeast Asia. Uber's stated priority markets, the Middle East, South Korea, and Argentina exclude the region, and Delivery Hero's Foodpanda operations remain subscale relative to Grab's market-leading position, with ~70% mobility share and 55% food delivery share.
US and Southeast Asian ride-hailing platforms continued to improve profitability in 2Q26. Uber led in scale and profitability, reporting 2Q26 Adjusted EBITDA of USD2.82bn (+33% y/y, ~2% above consensus), driven by continued operating leverage across Mobility and Delivery, coupled with AI-related productivity gains. Lyft posted 2Q26 Adjusted EBITDA of USD177mn (+37% y/y, beating consensus), supported by 23% Gross Bookings growth and double-digit active rider expansion (+17% y/y to a record 30.5mn). Grab delivered 2Q26 Adjusted EBITDA of USD168mn (+54% y/y, ~5% above consensus), driven by lower-than-expected corporate costs and a narrower Financial Services loss, Grab also raised FY26F Adjusted EBITDA guidance to USD720–740mn (44–48% y/y growth, up from USD700–720mn).
Southeast Asia impact remains limited as Uber focuses on global consolidation. More importantly, Uber has a financial disincentive to compete aggressively against Grab in Southeast Asia as its ~13.5% economic stake in Grab is worth ~USD1.6bn, more than double the value of Foodpanda’s Southeast Asian business. This is reinforced by the fact that Uber is barred from competing with Grab in its core markets for 12 months even if it fully exits its stake. This raises the possibility of regulatory rejection of the deal or Uber may end up winding down Foodpanda's Southeast Asian operations if it gets the approval. We continue to view Uber's Grab stake as a passive investment rather than a strategic lever.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.