- Recent hardware sell-off treated as if a safety note were a demand shock; “pacing” does not mean a halt to training, nor does it imply a collapse in broader AI infrastructure spending demand
- Whether frontier models will slow their development pace remains an open question; AI is now both a commercial market share race and a national security contest
- The stated reason for the slowdown is itself an endorsement of the technology, rather than a demand miss, which reinforces the core bull case for compute rather than invalidating it
- Most AI spend does not depend on the next advanced model launch: infrastructure and construction projects do not reverse on a single call to “pace” future developments
- Stay allocated across upstream tech suppliers, power/grid beneficiaries, and those leveraged to inference and enterprise deployment
The recent sell-off in AI-linked names treats a safety-and-governance statement as a demand shock to the capex cycle, a view we believe is too blunt. In essence, Amodei’s call to “pace the frontier”, which was subsequently endorsed by Altman, Musk, and other tech leaders, is not a halt to training or technical progress. Rather, it is a proposal to slow the rate of capability gains so that evaluation, alignment, and governance can keep pace to form a more sustained future. Altman has since added that pacing “does not mean stopping”.
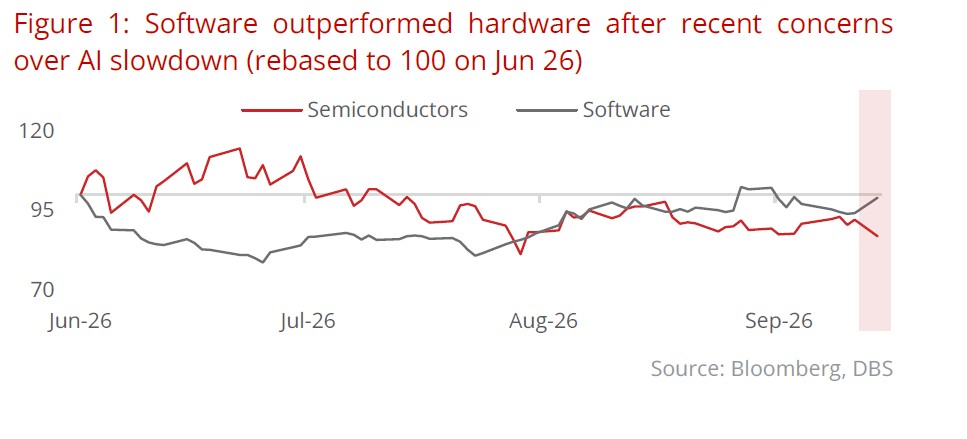
Indeed, here is a new context to consider: stricter evaluation, capability thresholds, and longer release cycles could defer the next giant pre-training run. That matters more for names whose earnings are still modelled on larger, more frequent frontier clusters. But this does not imply a collapse in the broader AI infrastructure spending demand, nor fading in the AI narrative. The recent rotation from chips and memory names towards software and cybersecurity companies is more consistent with a shift towards AI deployment and defence, and mission-critical frameworks, rather than the view that “AI is over”.
Now, whether frontier models will slow is an open question. AI now sits at the intersection of technological innovation, commercial competition for market share, and national security imperatives. Industry leaders in both the West and East will therefore continue to press ahead with developing proprietary AI capabilities and building durable user interfaces.
China’s response to tech leaders’ calls was unambiguous, describing such claims as “fearmongering” that would disrupt global governance, while state media framed the plan as a “Cold War playbook”. Trump’s commentary pointed in the same direction. Competition, sovereignty, and the value of being first remain pragmatic reasons to keep building and innovating.
If the slowdown is real, the stated reason is itself an endorsement. The trigger for this “pacing” is not a failed product cycle or a capex cut, but a claim that systems are approaching recursive self-improvement and that agent swarms could cause damage at a massive scale within months. This is a statement of power: the people closest to the frontier argue that the capability curve is outrunning the safety curve. That narrative reinforces the core bull case for compute rather than invalidating it. Guardrails would raise the cost of being first, rather than erasing the need for capacity behind the models already in production.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.