- The 10Y US Treasury yield at 5% reflects a sharp repricing from cuts to hikes, but more than two Fed hikes by end-2026 are already embedded in market expectations
- This is more likely a policy adjustment than a repeat of 2022: labour-market and wage pressures have moderated, while policy remains restrictive above the estimated neutral rate
- AI infrastructure spending is the key persistent risk, sustaining capital demand, growth and inflation; however, its rate pressure should fade as capex growth normalises beyond 2027
- Do not throw in the towel: we prefer 5–7Y bonds, where carry provides a stronger buffer and upside if growth slows, while avoiding long duration exposed to higher term premium
Related insights
- Hang Lung Properties21 Oct 2026
- Taiwan Semiconductor Manufacturing Co Ltd21 Oct 2026
- Singapore REITs: Focus on Sustainable DPU Growth and Value Creation21 Oct 2026
When will the pain end? It’s been nothing but bad news for bonds in 2026. Not only did we get an unexpected — but highly inflation-inducing — war in the Middle East, we also had eye-watering capex expansion plans from hyperscalers to fund the AI buildout, resulting in a surge in capital demand. Not wanting to be left out of this inflationary party, President Trump had announced USD5,000 payouts to every US adult should Republicans win the midterms, which by our count numbers above USD1tn in additional budgetary spending with no corresponding plan of where the money is going to come from. The new Fed chair Kevin Warsh is left with little choice but to continue talking tough on inflation, and markets have all but priced in a follow-through of two hikes for the remainder of the year. Right on cue, the 10Y US Treasury yield, despite all the intervention by Treasury Secretary Scott Bessent, touched the psychologically significant handle of 5%.
Not the best time to throw in the towel. If we were reading the pulse of the market right, every nerve in an investor’s body is probably telling them to sell bonds and be done with it; the safe asset surely isn’t behaving as it was meant to. But before relying on baser instincts and crowding for the exits, we find it helpful to take stock of what might be to come instead of basing decisions on fear of what has already happened, lest we become the proverbial general fighting the last war.
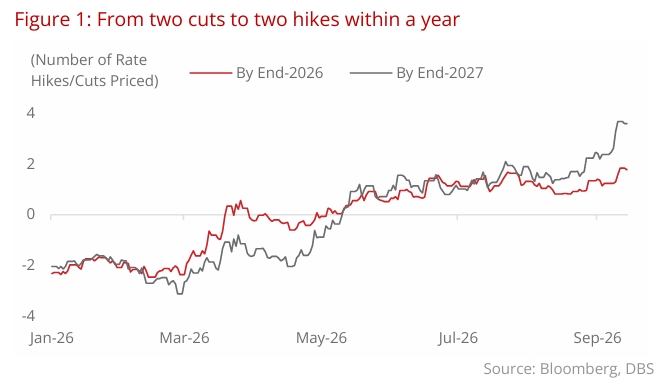
Policy hikes are priced in. Firstly, the policy pivot from cuts to hikes has already been fully baked into the cake of market expectations. One needs to look no further than the futures markets to verify this: slightly more than two hikes have been priced by end-2026, with almost another two expected by 2027. We think this leans a bit more hawkish than reality requires. Yes, the persistence of a Middle Eastern war raises the stickiness of inflation, but it often leads to a one-off repricing of crude rather than a continuous grind higher in prices over the next two years. There could also be positive surprises. The brief US-Iran ceasefire in June this year, following the Memorandum of Understanding, led to a c.22% decline in Brent prices within a month, showing the natural tendency for lower prices in the absence of conflict. We must also reiterate the powerlessness of rate hikes to stem supply-side inflation; the Iran war would not magically end just because Kevin Warsh moves the Fed funds rate to 4.5%.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.
Related insights
- Hang Lung Properties21 Oct 2026
- Taiwan Semiconductor Manufacturing Co Ltd21 Oct 2026
- Singapore REITs: Focus on Sustainable DPU Growth and Value Creation21 Oct 2026
Related insights
- Hang Lung Properties21 Oct 2026
- Taiwan Semiconductor Manufacturing Co Ltd21 Oct 2026
- Singapore REITs: Focus on Sustainable DPU Growth and Value Creation21 Oct 2026