

- Equities: Global equities rallied last week, driven by PBOC’s policy stimulus and government’s strong commitment to meet its 2024 economic growth target
- Credit: With the Fed lowering rates, IG credit is catching up to short-dated credit due to its higher sensitivity to rate cuts; a barbell strategy, balancing both short and long durations, may optimise returns
- FX: DXY to test support level at 100 after failing to push above 101 over past fortnight; USD/CNH to extend its fall below 7.00 following last week’s 0.9% decline
- Rates: Loose financial conditions and stable data points to drive US yields higher; steepening—which played out significantly over past three months—to take a pause
- The Week Ahead: Keep a lookout for US Change in Nonfarm Payrolls; Japan Jobless Rate
相關見解
- 每周外匯速遞 - 聚焦聯儲局會議14 Sep 2026
- 美元和港元何去何從?01 Sep 2026
- 黃金:光華內斂,無需贅飾20 Aug 2026
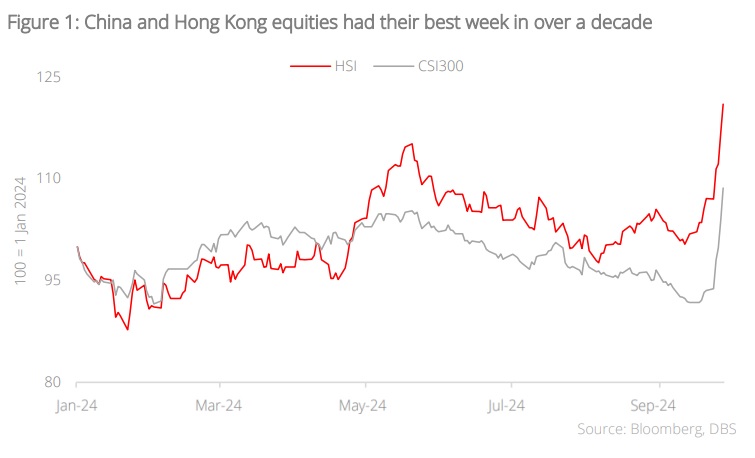
China’s supportive policies lift markets. Global equity markets extended their upward trajectory last week, buoyed by China’s policy stimulus aimed at reviving its struggling economy. The People’s Bank of China (PBOC) lowered its reserve requirement ratio (RRR) by 50 bps, reduced its seven-day reverse repo rate by 20 bps and cut its medium-term lending facility rate by 30 bps. Furthermore, in the Politburo meeting last Thursday, China’s leaders emphasised the need to drive recovery in their property market and vowed to deploy the necessary fiscal spending to achieve its 2024 economic growth target of 5%. This fuelled optimism in the China equities market with CSI 300 and SHCOMP surging 15.7% and 12.8% respectively.
Major equity indices across regions also notched positive performances last week. The NASDAQ gained 1.0% while the S&P 500 and Dow Jones were up 0.6%. In Europe, the Stoxx 600 and FTSE 100 rose 2.7% and 1.1% respectively. Markets also ended the week positively in Japan with the Nikkei-225 surging 5.6%.
Topic in focus: China Equities – Markets rally on policy easing. The PBOC has recently announced a series of policy easing measures, including the reduction of the RRR and adjustments to policy and mortgage rates. These efforts aim to stimulate investment, enhance liquidity, and restore confidence in financial markets. Coupled with other supportive tailwinds such as the US Fed’s rate cut cycle, a weakening dollar, and investors’ underweight positioning in China equities, China and Hong Kong equities rallied significantly last week; the Hang Seng Index and CSI300 gained 13.0% an 15.7% for the week ending 27 Sep.
While these policies take aim at the sustained recovery of the stock market and broader GDP growth, their effectiveness and successful implementation remain to be seen. Nonetheless, these recent steps have undoubtedly boosted near-term sentiment and raised market expectations. For clients who are underinvested in China equities, this presents an opportunity to add large-cap and index heavy-weights such as technology leaders and quality growth stocks that are at the fore of favourable liquidity flows. On the income side, stay invested in large state banks for reliable dividend yields amid a falling rate environment.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
本資訊是由星展銀行集團公司(公司註冊號: 196800306E)(以下簡稱“星展銀行”)發佈僅供參考。其所依據的資訊或意見搜集自據信可靠之來源,但未經星展銀行、其關係企業、關聯公司及聯屬公司(統稱“星展集團”獨立核實,在法律允許的最大範圍內,星展集團針對本資訊的準確性、完整性、時效性或者正確性不作任何聲明或保證(含明示或暗示)。本資訊所含的意見和預期內容可能隨時更改,恕不另行通知。本資訊的發佈和散佈不構成也不意味著星展集團對資訊中出現的任何個人、實體、服務或產品表示任何形式的認可。以往的任何業績、推斷、預測或結果模擬並不必然代表任何投資或證券的未來或可能實現的業績。外匯交易蘊含風險。您應該瞭解外匯匯率的波動可能會給您帶來損失。必要或適當時,您應該徵求自己的獨立的財務、稅務或法律顧問的意見或進行此類獨立調查。
本資訊的發佈不是也不構成任何認購或達成任何交易之要約、推薦、邀請或招攬的一部分;在以下情況下,本資訊亦非邀請公眾認購或達成任何交易,也不允許向公眾提出認購或達成任何交易之要約,也不應被如此看待:例如在所在司法轄區或國家/地區,此類要約、推薦、邀請或招攬係未經授權;向目標物件進行此類要約、推薦、邀請或招攬係不合法;進行此類要約、推薦、邀請或招攬係違反法律法規;或在此類司法轄區或國家/地區星展集團需要滿足任何註冊規定。本資訊、資訊中描述或出現的服務或產品不專門用於或專門針對任何特定司法轄區的公眾。
本資訊是星展銀行的財產,受適用的相關智慧財產權法保護。本資訊不允許以任何方式(包括電子、印刷或者現在已知或以後開發的其他媒介)進行複製、傳輸、出售、散佈、出版、廣播、傳閱、修改、傳播或商業開發。
星展集團及其相關的董事、管理人員和/或員工可能對所提及證券擁有部位或其他利益,也可能進行交易,且可能向其中所提及的任何個人或實體提供或尋求提供經紀、投資銀行和其他銀行或金融服務。
在法律允許的最大範圍內,星展集團不對因任何依賴和/或使用本資訊(包括任何錯誤、遺漏或錯誤陳述、疏忽或其他問題)或進一步溝通產生的任何種類的任何損失或損害(包括直接、特殊、間接、後果性、附帶或利潤損失)承擔責任,即使星展集團已被告知存在損失可能性也是如此。
若散佈或使用本資訊違反任何司法轄區或國家/地區的法律或法規,則本資訊不得為任何人或實體在該司法轄區或國家/地區散佈或使用。本資訊由 (a) 星展銀行集團公司在新加坡;(b) 星展銀行(中國)有限公司在中國大陸;(c) 星展銀行(香港)有限責任公司在中國香港[DBS CY1] ;(d) 星展(台灣)商業銀行股份有限公司在台灣;(e) PT DBS Indonesia 在印尼;以及 (f) DBS Bank Ltd, Mumbai Branch 在印度散佈。
相關見解
- 每周外匯速遞 - 聚焦聯儲局會議14 Sep 2026
- 美元和港元何去何從?01 Sep 2026
- 黃金:光華內斂,無需贅飾20 Aug 2026
相關見解
- 每周外匯速遞 - 聚焦聯儲局會議14 Sep 2026
- 美元和港元何去何從?01 Sep 2026
- 黃金:光華內斂,無需贅飾20 Aug 2026