
Related insights
- Philippines: BSP steps up rate defence as challenges mount 23 Oct 2026
- HKD and CNH rates – Pay opportunities emerge 23 Oct 2026
- Research Library23 Oct 2026
The Bank of Korea maintained its base rate at 3.00% as expected on October 22, pausing after back-to-back rate hikes in July and August. We view this as an inter-cycle pause to assess the impact of the previous hikes, with the tightening bias remaining intact. The BOK signalled that 2026 and 2027 GDP growth could exceed its current forecasts of 3.3% and 2.9%, respectively, while 2027 CPI inflation could also come in above its current projection of 2.3%. This points to potential upward revisions to the BOK’s economic forecasts at its next quarterly review in November.
We maintain our call for a final 25bp rate hike in November, bringing the policy rate to 3.25% by year-end. We expect 3.25% to be the terminal rate, consistent with our view that annual CPI inflation will remain below 3%. The swap market appears to underestimate the near-term pace of tightening, pricing in no rate move over the next month, while overestimating the terminal rate at around 3.5% over the next 12 months.
The BOK appears comfortable with the KRW’s recent appreciation. At the press conference, the governor noted that a stronger KRW would help contain imported inflation and boost household purchasing power. The KRW has appreciated by 15% against the USD over the past three months. Over the same period, South Korea’s trade surplus widened from USD30.7bn in July to USD50bn in September, as surging memory chip exports more than offset higher energy import costs. The current account surplus is on track to reach a record USD400bn this year, equivalent to a striking 20% of GDP.
We see tactical steepening opportunities in the KRW curve at this juncture. Note that the 3Y/10Y KRW NDIRS spread has flattened from 21 bps on October 9 to 9 bps as of yesterday. First, the BOK slightly hawkish stance increases the odds of a November rate hike—an outcome not yet fully priced in by the swap market. Second, investors are eyeing a tactical rebound in the KOSPI following a 21% MTD correction; a recovery in equities will likely provide upward impetus to long-end KRW rates. Should the USD curve resume its steepening trend, the high-beta KRW rates are expected to follow suit.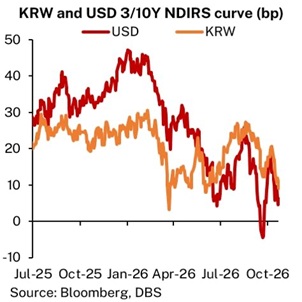


Topic
Explore more
E & S Macro StrategyGENERAL DISCLOSURE/ DISCLAIMER (For Macroeconomics, Currencies, Interest Rates, Digital Assets or Commodities)[1]
The information herein is published by DBS Bank Ltd and/or DBS Bank (Hong Kong) Limited (each and/or collectively, the “Company”). It is based on information obtained from sources believed to be reliable, but the Company does not make any representation or warranty, express or implied, as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions expressed are subject to change without notice. This research is prepared for general circulation. Any recommendation contained herein does not have regard to the specific investment objectives, financial situation and the particular needs of any specific addressee. The information herein is published for the information of addressees only and is not to be taken in substitution for the exercise of judgement by addressees, who should obtain separate legal or financial advice. The Company, or any of its related companies or any individuals connected with the group accepts no liability for any direct, special, indirect, consequential, incidental damages or any other loss or damages of any kind arising from any use of the information herein (including any error, omission or misstatement herein, negligent or otherwise) or further communication thereof, even if the Company or any other person has been advised of the possibility thereof. The information herein is not to be construed as an offer or a solicitation of an offer to buy or sell any securities, futures, options or other financial instruments or to provide any investment advice or services. The Company and its associates, their directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned herein and may also perform or seek to perform broking, investment banking and other banking or financial services for these companies. The information herein is not directed to, or intended for distribution to or use by, any person or entity that is a citizen or resident of or located in any locality, state, country, or other jurisdiction (including but not limited to citizens or residents of the United States of America) where such distribution, publication, availability or use would be contrary to law or regulation. The information is not an offer to sell or the solicitation of an offer to buy any security in any jurisdiction (including but not limited to the United States of America) where such an offer or solicitation would be contrary to law or regulation.
[#for Distribution in Singapore] This report is distributed in Singapore by DBS Bank Ltd (Company Regn. No. 196800306E) which is Exempt Financial Advisers as defined in the Financial Advisers Act and regulated by the Monetary Authority of Singapore. DBS Bank Ltd may distribute reports produced by its respective foreign entities, affiliates or other foreign research houses pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed in Singapore to a person who is not an Accredited Investor, Expert Investor or an Institutional Investor, DBS Bank Ltd accepts legal responsibility for the contents of the report to such persons only to the extent required by law. Singapore recipients should contact DBS Bank Ltd at 65-6878-8888 for matters arising from, or in connection with the report.
DBS Bank Ltd., 12 Marina Boulevard, Marina Bay Financial Centre Tower 3, Singapore 018982. Tel: 65-6878-8888. Company Registration No. 196800306E.
DBS Bank Ltd., Hong Kong Branch, a company incorporated in Singapore with limited liability. 18th Floor, The Center, 99 Queen’s Road Central, Central, Hong Kong SAR.
DBS Bank (Hong Kong) Limited, a company incorporated in Hong Kong with limited liability. 11th Floor, The Center, 99 Queen’s Road Central, Central, Hong Kong SAR.
[1] This disclaimer may not apply if the applicable assets fall within the definition of 'financial instruments' that are set out in Article 2(1) EU MAR (e.g. financial instruments that are traded on a regulated market, MTF or OTF, etc.). Section C of Annex I of MiFID2 specifies these 'financial instruments'.
Related insights
- Philippines: BSP steps up rate defence as challenges mount 23 Oct 2026
- HKD and CNH rates – Pay opportunities emerge 23 Oct 2026
- Research Library23 Oct 2026
Related insights
- Philippines: BSP steps up rate defence as challenges mount 23 Oct 2026
- HKD and CNH rates – Pay opportunities emerge 23 Oct 2026
- Research Library23 Oct 2026