- China/HK equities saw a sharp sell-off in recent weeks as investors reassess near-term policy outlook and earnings expectations in a “higher-for-longer” interest rate environment
- The weakness reflects faded stimulus hopes after a solid 3Q GDP print, limited policy signals from regulators, early earnings disappointments, and a wait-and-see stance amongst investors in an elevated global yield environment
- Much of the negative news appears to be already priced in; China’s medium-term outlook remains supported by exports and technology upgrading, while onshore regulators are actively cushioning downside risks
- The recent correction is an opportunity to sharpen portfolio quality via selective accumulation in technology, high-quality platform names, and financials; onshore continues to offer stronger fundamentals and policy alignment
Related insights
- Fixed Income Weekly: Curve Steepening Following Fed Pause29 Oct 2026
- New World Development29 Oct 2026
- Baidu Inc29 Oct 2026
A sharp retreat. Mainland China and Hong Kong (HK) equities have come under renewed pressure as investors reassess policy expectations and earnings delivery in a “higher-for-longer” interest rate environment. The CSI 300 reached technical bear territory yesterday, down c.20% from its June high, while the Hang Seng Index tested multi-month lows with the Hang Seng Tech Index sliding to multi-year lows as well. Technology shares bore the brunt with selling extended to previously favoured AI build-out beneficiaries.
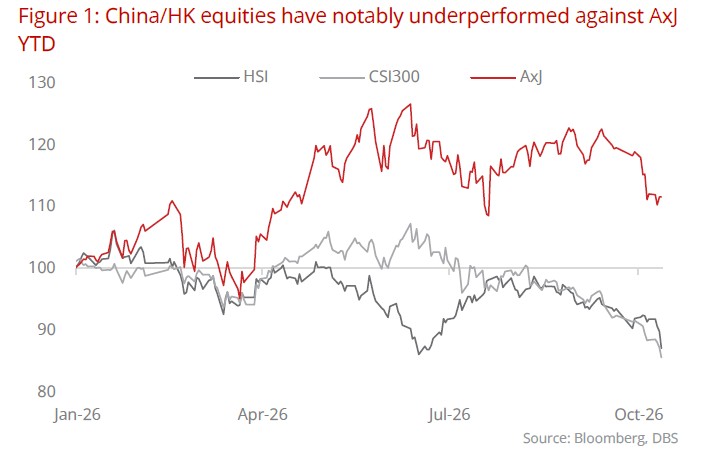
Expectation reset. Several overlapping factors are contributing to the weakness. Solid 3Q GDP growth in China tempered hopes for an imminent broad-based stimulus package. Policy signals from the Financial Street Forum (e.g. PBOC’s study of shifting towards the overnight reverse-repo rate as the main policy rate) appears to focus on refinement rather than meaningful easing. SAMR’s recent symposium with major online platforms on product and service quality has added near-term caution in the technology and platform space. Early earnings disappointments, notably CATL’s 3Q26 earnings miss and underwhelming market result previews on internet names (e.g. Tencent, Alibaba and Baidu) have set a softer tone ahead of results season. Continually elevated global bond yields have further kept investors sidelined.
Corrections appear overdone. While these factors may continue to weigh on China/HK equities’ near-term performance, the scale of the recent correction appears overdone relative to its underlying fundamentals. Much of the policy uncertainty, earnings caution, and yield pressure are already reflected in the price with valuations in technology and platforms having compressed meaningfully. China’s medium-term economic outlook remains intact, supported by export resilience and structural progress in technology and industrial upgrading. Regulators have also demonstrated a clear intent to cushion downside risk (with possible national team buying in broad-based and technology-based onshore ETFs in recent trading sessions). Lower valuations post-correction, therefore, improves the risk-reward for selective accumulation, rather than signal a fundamental deterioration in the growth or policy roadmap.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.
Related insights
- Fixed Income Weekly: Curve Steepening Following Fed Pause29 Oct 2026
- New World Development29 Oct 2026
- Baidu Inc29 Oct 2026
Related insights
- Fixed Income Weekly: Curve Steepening Following Fed Pause29 Oct 2026
- New World Development29 Oct 2026
- Baidu Inc29 Oct 2026