

- US: The Fed delivered an unanimous 25 bps rate hike amid persistent inflation; we expect two additional hikes to a 4.5% peak, though the financial market, AI, debt, labour, and geopolitical shocks could derail this path
- Eurozone: 1H26 resilience reinforced our marginal 2026 GDP upgrade; the ECB is likely to deliver an additional 50 bps of rate hikes, likely at its Dec 2026 and Mar 2027 meetings
- China: Exports kept growth afloat, with industrial activity improved despite soft domestic demand. Consumption, investment, and credit demand stayed subdued.
- India: August inflation rose 4.8% y/y, the highest since Dec 2024; a sustained rise in crude prices, firm domestic growth, and signs of broadening in core pressures strengthen the case for a shallow 50 bps hike in 2HFY27, making October’s meeting a live one
Related insights
- DEER: Policy and the undervalued JPY 22 Sep 2026
- USD Rates: Optimistic start22 Sep 2026
- Hoping for relief to shift from the Fed to geopolitics22 Sep 2026
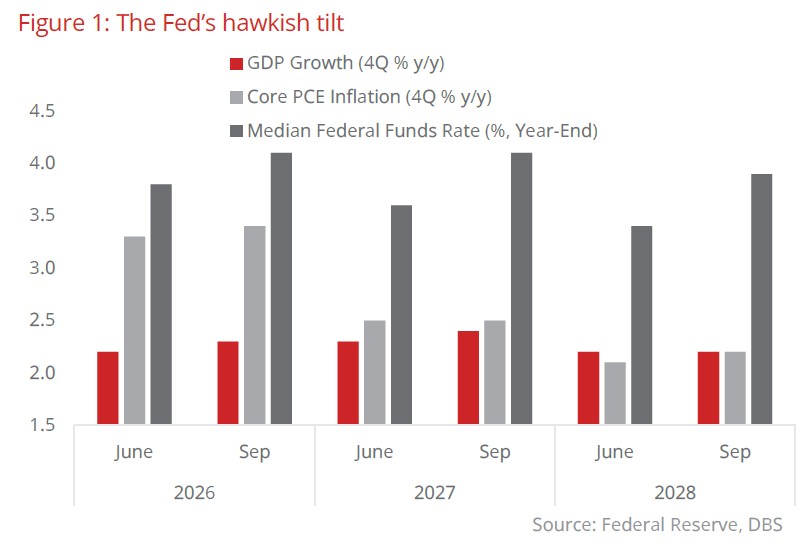
US: Unanimous rate rise sets up one more hike this year. The US Federal Reserve delivered a widely anticipated rate hike at the conclusion of the 15-16 Sep FOMC meeting. We had expected a contentious outcome that could result in no change, but the entire committee came together to vote in favour of a rate hike. Persistent inflation, compounded by an array of demand (AI build-out), supply (oil shock), and policy (tariffs) factors, has pushed the Fed into a corner that was not anticipated just six months ago. A 25 bps hike to 4% in the Fed Funds Rate set the stage for more hikes ahead, as reflected in the vast majority of the FOMC members’ projections.
We now pencil in one more rate hike this year and another early next year, taking the terminal rate of this short cycle to 4.5%. In making this call, we take note of the points made by Fed Chair Warsh last month – that monetary conditions are not tight, the pace of inflation returning towards the 2% target is yet to be satisfactory, and short-term interest rates remain the key tool to dealing with the Fed’s mandate. The latest statement also suggests sufficient comfort with GDP growth, consumption, the labour market, and productivity to retain a focus on inflation for the time being.
Much could cause this rate-hike path to be derailed. A large market sell-off, public debt crisis, AI-related cataclysmic event, slippage in the labour market, or major worsening of the geopolitical environment could force the Fed to shift its focus from inflation to economic stabilisation. At the other end of the risk spectrum, continued fiscal slippage and greater pressure on prices and wages due to the AI boom could leave the market unsatisfied even with the policy rate at 4.5%.
Bottom line, the about-turn by what had seemed like a dovish Fed Chair just a few months ago underscores the challenges embedded in this cycle. While inflation may be largely supply-side driven, there are enough risks to the inflation outlook to warrant more action in the coming months. This is particularly the case as the Fed’s leadership appears keen to stamp credibility in a vigorous manner.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.
Related insights
- DEER: Policy and the undervalued JPY 22 Sep 2026
- USD Rates: Optimistic start22 Sep 2026
- Hoping for relief to shift from the Fed to geopolitics22 Sep 2026
Related insights
- DEER: Policy and the undervalued JPY 22 Sep 2026
- USD Rates: Optimistic start22 Sep 2026
- Hoping for relief to shift from the Fed to geopolitics22 Sep 2026