

- After a strong rebound in 1H26, much of the easy recovery in residential prices has been banked and the market may enter a period of consolidation as rate uncertainty and concerns on tighter mainland capital controls take hold
- Improving leasing demand from financial institutions, declining vacancies in central, and sharply lower new supply underpin a constructive outlook for core office assets, though non-core districts take time to digest supply-demand imbalances
- Luxury retail and prime high-street locations continue to benefit from tourism recovery and affluent spending, whereas mass market malls face headwinds from northbound consumption, cross-border e-commerce and moderating RMB-driven demand
- The sector is set to take a breather; we recommend that investors stay nimble with a focus on quality landlords and developers that hold diverse portfolios and have strong balance sheets
Related insights
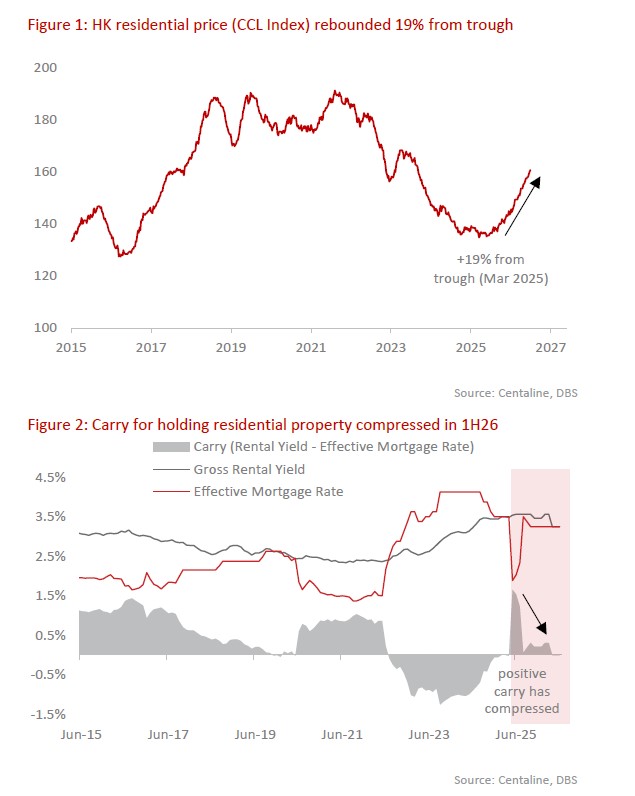
The Hong Kong property market enjoyed a vigorous 1H26 since our CIO Perspectives (Equity Strategy: Hong Kong Property's Year of Pivot, published in Feb 2026), with residential prices surging c.11% YTD, transactions hitting their highest 1H levels since 2021, and core office rents turning higher at last. However, 2H is likely to prove more subdued. Macroeconomic uncertainties, fidgety interest rate expectations, and the simple reality that much of the easy recovery has already been banked suggest a consolidation rather than another leg higher.
Residential: Softer momentum. After 16 consecutive months of price gains and more than 40,800 transactions completed in 1H26, the residential market is showing signs of consolidation. Enquiries cooled from June as equity markets turned volatile, interest rates expectations pivoted from cuts to hikes, and controls on China’s outbound investments tightened. These, together with the strong 1H26 price growth momentum, makes a period of consolidation ever so rational. Higher home prices also led to a drop in rental yield to 3.2%, flattening the gap with current mortgage rates thus narrowing carry, sidelining investors and users alike.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.