

Related insights
The cost of conflict. During the Vietnam War, “guns and butter” policy respected a simple trade off – more defence spending meant less handouts for the domestic economy. Today, however, trade-offs appear like a passé stance of excessive conservatism; if one possessed the world’s reserve currency, why not fund both guns and butter needs with debt? One needs to look no further than the US to see that this shift is already underway; President Trump’s passage of his landmark “One Big, Beautiful Bill Act” (butter) acted as no restraint on him starting a conflict in Iran (guns). There is however, one little snag – central bank independence. The inflationary consequence of war means that interest rates stay elevated, resulting in debt interest payments in the US now exceeding USD1tn a year and rising. This greatly reduces investors’ willingness to absorb sovereign debt since government bonds cannot be risk-free if the same government keeps adding to that risk with big, beautiful deficits.
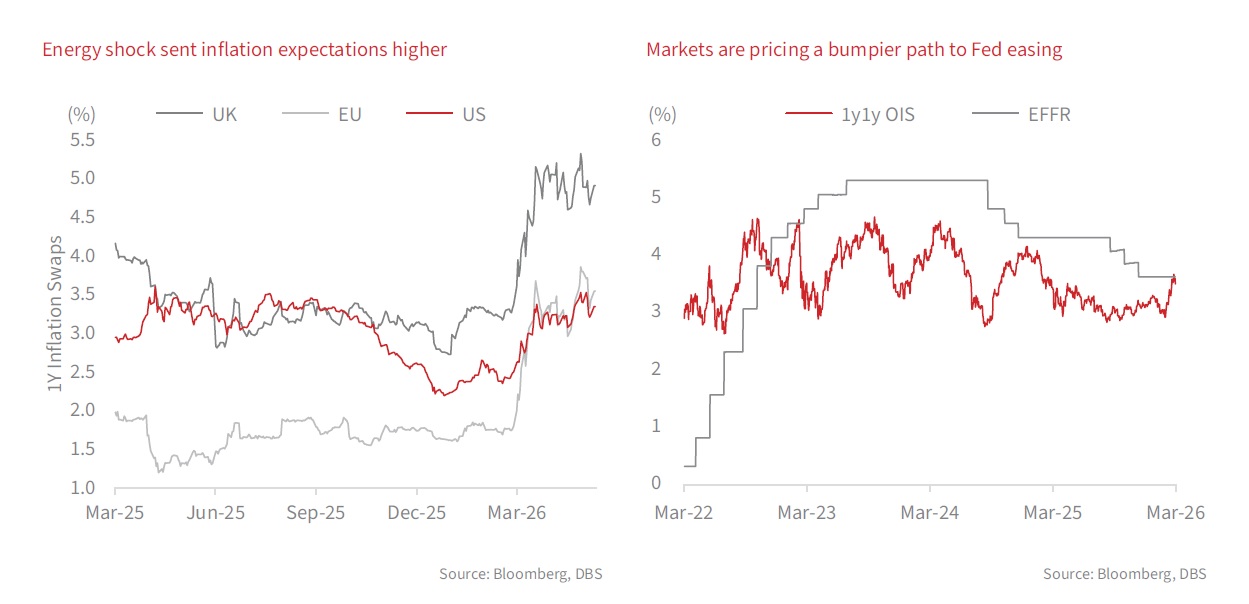
A crude awakening. This makes the outcome of the US-Iran war especially consequential to the outlook on fixed income. The ongoing conflict has not only (a) pushed oil prices (and hence, inflation) higher through supply disruptions and sanctions, but also (b) increases the need for defence spending – President Trump has already unveiled an unprecedented request for a USD1.5tn defence budget for 2027 – invariably adding to federal budget vulnerabilities. Even if a resolution emerges in the near term, supply may take some time to normalise, leaving sticky inflationary pressure as higher input costs squeeze margins and increase cost pass-through to consumers. Expectations are already rising, with inflation swaps showing a sharp increase in demand for inflation protection since March. This leaves the Federal Reserve with less room to cut rates as aggressively as markets had expected earlier this year. Noteworthily, the 1y1y OIS rate, which reflects market expectations for interest rates in the future, has moved above the effective federal funds rate for the first time in four years. This suggests investors are placing less confidence in a one-directional easing cycle, and are pricing either fewer cuts, or a higher-for-longer policy path.
Download the PDF to read the full report which includes coverage on Credit, FX, Rates, and Thematics.
Topic
The information published by DBS Bank Ltd. (company registration no.: 196800306E) (“DBS”) is for information only. It is based on information or opinions obtained from sources believed to be reliable (but which have not been independently verified by DBS, its related companies and affiliates (“DBS Group”)) and to the maximum extent permitted by law, DBS Group does not make any representation or warranty (express or implied) as to its accuracy, completeness, timeliness or correctness for any particular purpose. Opinions and estimates are subject to change without notice. The publication and distribution of the information does not constitute nor does it imply any form of endorsement by DBS Group of any person, entity, services or products described or appearing in the information. Any past performance, projection, forecast or simulation of results is not necessarily indicative of the future or likely performance of any investment or securities. Foreign exchange transactions involve risks. You should note that fluctuations in foreign exchange rates may result in losses. You may wish to seek your own independent financial, tax, or legal advice or make such independent investigations as you consider necessary or appropriate.
The information published is not and does not constitute or form part of any offer, recommendation, invitation or solicitation to subscribe to or to enter into any transaction; nor is it calculated to invite, nor does it permit the making of offers to the public to subscribe to or enter into any transaction in any jurisdiction or country in which such offer, recommendation, invitation or solicitation is not authorised or to any person to whom it is unlawful to make such offer, recommendation, invitation or solicitation or where such offer, recommendation, invitation or solicitation would be contrary to law or regulation or which would subject DBS Group to any registration requirement within such jurisdiction or country, and should not be viewed as such. Without prejudice to the generality of the foregoing, the information, services or products described or appearing in the information are not specifically intended for or specifically targeted at the public in any specific jurisdiction.
The information is the property of DBS and is protected by applicable intellectual property laws. No reproduction, transmission, sale, distribution, publication, broadcast, circulation, modification, dissemination, or commercial exploitation such information in any manner (including electronic, print or other media now known or hereafter developed) is permitted.
DBS Group and its respective directors, officers and/or employees may have positions or other interests in, and may effect transactions in securities mentioned and may also perform or seek to perform broking, investment banking and other banking or financial services to any persons or entities mentioned.
To the maximum extent permitted by law, DBS Group accepts no liability for any losses or damages (including direct, special, indirect, consequential, incidental or loss of profits) of any kind arising from or in connection with any reliance and/or use of the information (including any error, omission or misstatement, negligent or otherwise) or further communication, even if DBS Group has been advised of the possibility thereof.
The information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation. The information is distributed (a) in Singapore, by DBS Bank Ltd.; (b) in China, by DBS Bank (China) Ltd; (c) in Hong Kong, by DBS Bank (Hong Kong) Limited; (d) in Taiwan, by DBS Bank (Taiwan) Ltd; (e) in Indonesia, by PT DBS Indonesia; and (f) in India, by DBS Bank Ltd, Mumbai Branch.